
Golden Door Asset · Investment Committee Research Brief
GoDaddy Inc.
Published Oct 31, 2026 · Data as of Oct 31, 2026
GDDY · Research
GoDaddy Grew 6% With Almost No New Customers. The Toll Is the Domain Record, Not the Agentic Website Builder
GoDaddy added 0.4% more customers in nine months while ARPU rose 6.8%. Its new agentic website builder is 2.2% of recurring revenue, and 42.6% of the Q3 operating income jump came from lower amortization and stock pay.
Full Research & Archive: Ratings and research summaries stay free for everyone. Full Access unlocks the full research reports, the archive and the CSV export across 100+ software companies.
Explore Full Access →Reverse-DCF Valuation Expectations Gap
Discounted vs. Trailing Growth5-year unlevered DCF revenue CAGR hurdle implied by GoDaddy Inc. (GDDY) current enterprise value ($17.5B) at 3.0% terminal growth, compared against reported trailing YoY revenue growth and 1-year R&D payback.
- Implied 5Y CAGR Hurdle
- 1.1%
- Reported YoY Revenue Growth
- 6.7%
- Expectations Spread
- -5.6 pp
- Growth in total customers
- 0.4%
- Agentic website builder bookings run rate as a share of ARR
- 2.2%
- Owner cash
- $1.4B
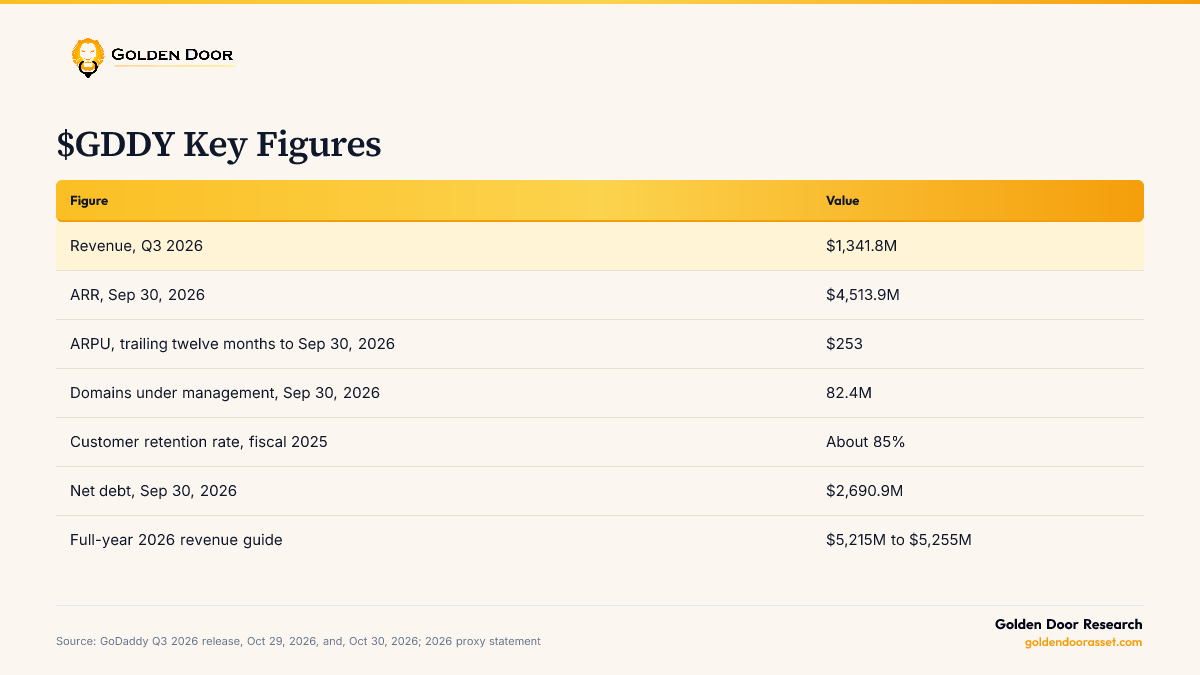
$1,341.8M
| Figure | Value |
|---|---|
| Revenue, Q3 2026 | $1,341.8M |
| ARR, Sep 30, 2026 | $4,513.9M |
| ARPU, trailing twelve months to Sep 30, 2026 | $253 |
| Domains under management, Sep 30, 2026 | 82.4M |
| Customer retention rate, fiscal 2025 | About 85% |
| Net debt, Sep 30, 2026 | $2,690.9M |
| Full-year 2026 revenue guide | $5,215M to $5,255M |
Source: GoDaddy Q3 2026 release, Oct 29, 2026, and, Oct 30, 2026; 2026 proxy statement
Golden Door Researchgoldendoorasset.com
$GDDY key figures, latest filings.
1. Verdict and what this piece answers
Verdict: Hold off, conviction 3 of 5. The anchor is trailing twelve-month owner cash of $1.4B, more precisely $1,436.7M, meaning operating cash flow less all capex, including ICANN registry application fees, less stock pay, our calculation [1][3]. Owner cash has been positive in each of the last five full years, rising from $570.3M in fiscal 2021 to $1,257.7M in fiscal 2025 [3].
GoDaddy printed third-quarter 2026 revenue of $1.3B, up 6.0%, operating income up 22.2% and net income up 24.4%, and said it expects to finish the year toward the higher end of its $5.2B to $5.3B revenue range [2]. Read quickly, that is a mature company that found a second wind.
This piece asks two narrower questions. Where is the growth actually coming from?
And how much of the profit jump is the business, and how much is accounting running off?
The answers are less exciting than the headline and more durable. GoDaddy added just 75 thousand customers in nine months, a 0.4% gain on a base of 20.4M, while average revenue per user rose 6.8% to $253 [1][2].
Nearly all of the growth is existing customers paying more: more products, higher renewal prices and a domain aftermarket that added $14.3M in the quarter [1]. On profit, amortization of acquired intangibles fell to $2.7M from $17.3M and stock pay fell to $67.3M from $79.6M; together those two lines explain 42.6% of the $65.8M rise in operating income, our calculation [1][2].
Strip both out and operating profit before depreciation, amortization and stock pay grew 9.3%, our calculation [2]. Our view: the market is debating whether GoDaddy's agentic website builder can turn it into a superintelligence growth company.
The filings say it is something steadier: a toll on 82.4M domain records that reprices a fixed customer base every year, with the new product still only 2.2% of recurring revenue.
Company Profile
GDDY Stock Profile →Related Coverage & Peer Deep-Dives
View All →Claude Sheets Still Sends Serious Work Back to Excel, but Microsoft's Owner Cash Fell 46.64% in Two Years and Its Market Value Assumes 57% Yearly Growth
Anthropic's new sheets still send serious work back to Excel, but owner cash after capex and stock pay fell 46.64% in two years and the market value assumes about 57% yearly growth. Avoid, conviction 3 of 5.