
Golden Door Asset · Investment Committee Research Brief
ServiceTitan, Inc.
Published Oct 29, 2026 · Data as of Oct 29, 2026
TTAN · Research
ServiceTitan grows 21% but stock pay runs at 1.88x its free cash
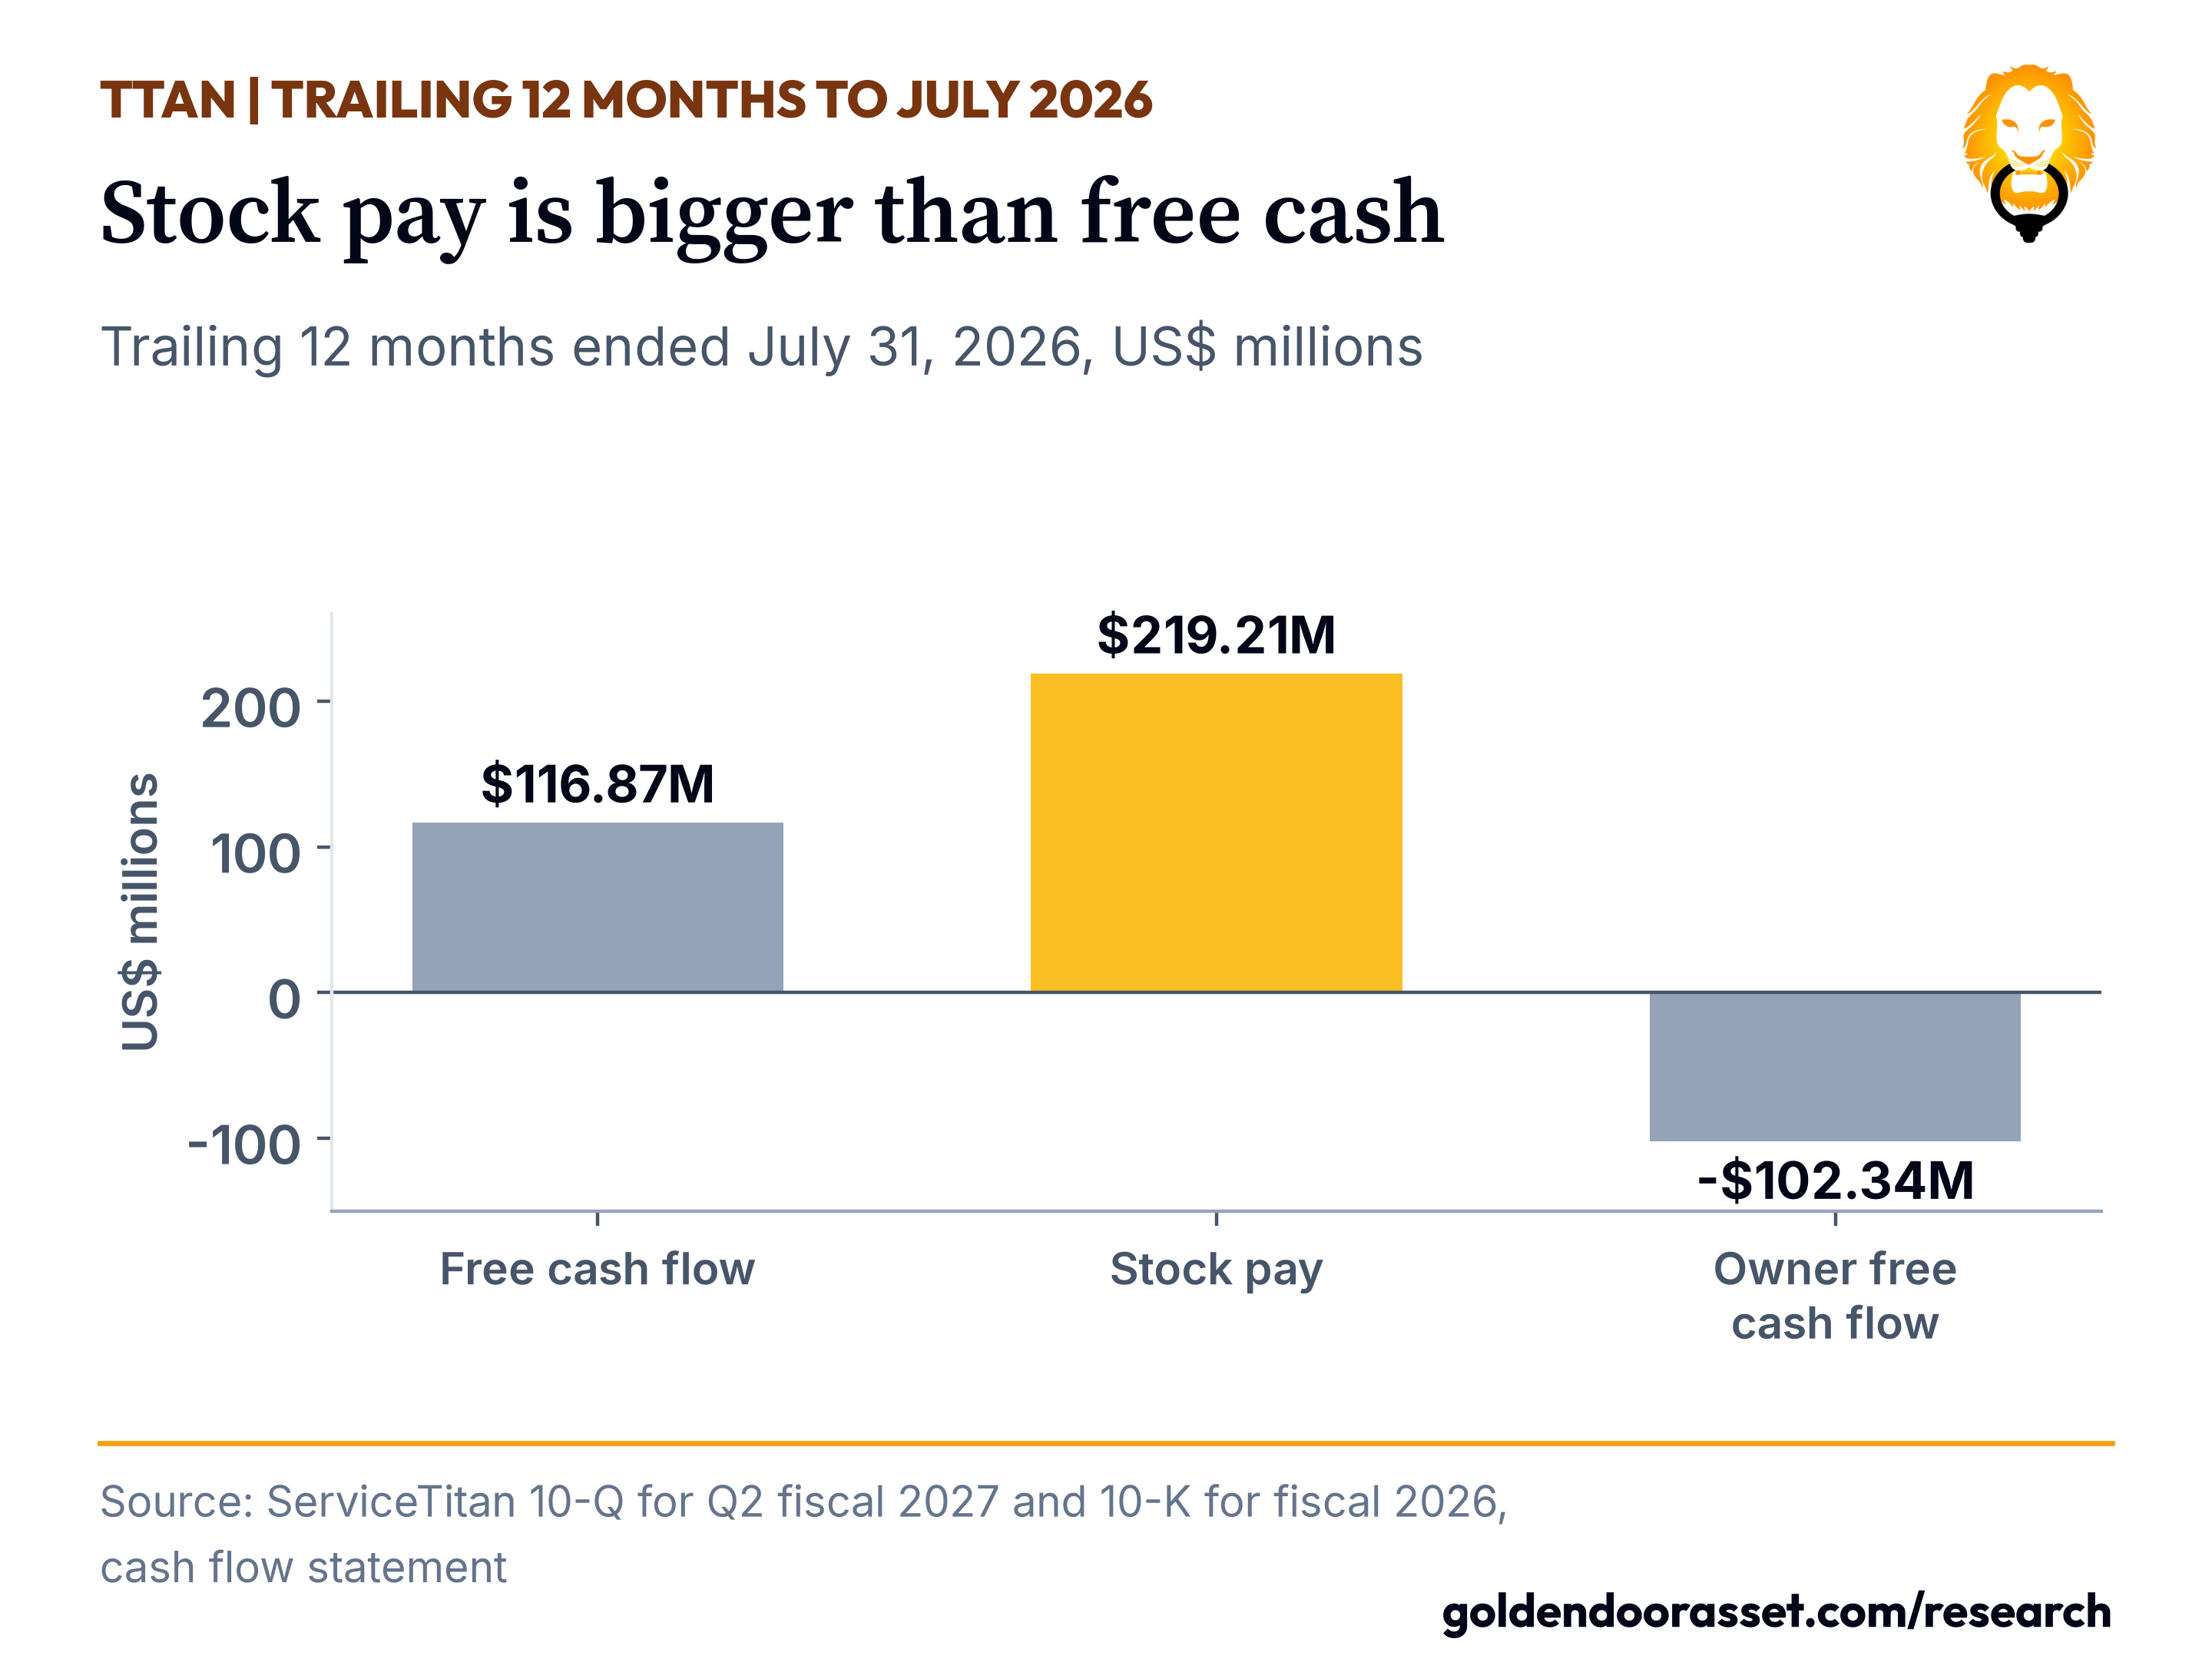
ServiceTitan, the operating system for plumbing, HVAC and other trades contractors, grew revenue 20.9% in its fiscal second quarter, with payments and financing revenue up 24%. It produced about $117M of trailing free cash flow but paid about $219M in stock, so owners kept nothing after stock pay.
Full Research & Archive: Ratings and research summaries stay free for everyone. Full Access unlocks the full research reports, the archive and the CSV export across 100+ software companies.
Explore Full Access →Reverse-DCF Valuation Expectations Gap
Discounted vs. Trailing Growth5-year unlevered DCF revenue CAGR hurdle implied by ServiceTitan, Inc. (TTAN) current enterprise value ($7.3B) at 3.0% terminal growth, compared against reported trailing YoY revenue growth and 1-year R&D payback.
- Implied 5Y CAGR Hurdle
- 18.2%
- Reported YoY Revenue Growth
- 27.1%
- Expectations Spread
- -8.9 pp
1. Summary
The question this piece answers: ServiceTitan holds the records and the payments for the trades businesses that run on it, and it is growing above 20%. Does that position justify about $7.32B of enterprise value when stock pay is almost twice its free cash flow?
What you will get from each section. The Thesis explains why the system a contractor uses to book, dispatch, invoice and get paid is the kind of gate superintelligence agents must pass through, and scores ServiceTitan on our four gate tests. The Valuation sets today's multiples against a five-year bear, base and bull case built on owner free cash flow, which is negative today.
The Financial update shows where growth came from and where the losses narrowed. The Risks develop the three threats that matter most: stock pay and founder control, reliance on one payments processor and the trades cycle, and the cost and uncertainty of the agent build.
The last section names the trigger that would change our call.
Our position: watch. The business passes the gate test, but stock pay of 1.88x free cash flow means our base case lands at 0.80x of today's value, and we want to see stock pay fall below free cash flow before we would own it.
Key numbers
Q2 fiscal 2027 revenue rose 20.9% to $292.76M, and usage revenue from payments and financing rose 24.41% to $72.12M [1].
The net dollar retention rate was over 110% for the quarter [1].
The operating loss narrowed to $27.55M from $34.77M [1].
Trailing free cash flow was about $116.87M and stock pay $219.21M, so owner free cash flow was about negative $102.34M, our calculation [1][2].
Cash and cash equivalents were $479.54M with no loans outstanding [1].
Company Profile
TTAN Stock Profile →Related Coverage & Peer Deep-Dives
View All →Fair Isaac: Hold as 51.7% Credit-Scoring Operating Margin Trades at 1.71x Base DCF
FICO converts $2.53B of FY2026 revenue into a 51.7% GAAP operating margin and $884.5M of owner cash on just $2.1M of capex, yet at $1,653.48 shares trade 71.2% above our $965.54 base DCF amid mortgage regulatory scrutiny.