
Golden Door Asset · Investment Committee Research Brief
AvePoint, Inc.
Published Oct 28, 2026 · Data as of Oct 28, 2026
AVPT · Research
AvePoint Grew ARR 27% to $465.1M With No Debt and $417.25M of Cash
AvePoint's SaaS revenue grew 27.41% in Q2 as customers move data governance to the cloud. GAAP EBITDA of $52.06M is thin against operating cash flow of $104.69M, and a tax benefit inflated net income.
Full Research & Archive: Ratings and research summaries stay free for everyone. Full Access unlocks the full research reports, the archive and the CSV export across 100+ software companies.
Explore Full Access →Reverse-DCF Valuation Expectations Gap
Aligned With Fundamentals5-year unlevered DCF revenue CAGR hurdle implied by AvePoint, Inc. (AVPT) current enterprise value ($3.4B) at 3.0% terminal growth, compared against reported trailing YoY revenue growth and 1-year R&D payback.
- Implied 5Y CAGR Hurdle
- 20.0%
- Reported YoY Revenue Growth
- 21.6%
- Expectations Spread
- -1.6 pp
| Scorecard | Read |
|---|---|
| Thesis | ARR growth of 27% is carrying a business whose GAAP earnings are still thin, and cash, not EBITDA, is the better read |
| What proves it wrong | ARR growth, adjusted for currency, falls below 20% from 24%, or SaaS gross margin slips below 80% |
| Next catalyst | Q3 2026 results, Thursday Nov 5, 2026 after the close (company announcement, Oct 13) |
| Key multiple | 58.88x EV / GAAP EBITDA of $52.06M |
| Debt | $0. No borrowings under the loan agreement at Jun 30, 2026 |
| Stock pay | $35.39M from the cash flow line, 7.59% of revenue |
Source: AvePoint, Inc. filings and Golden Door Asset research.
What AvePoint sells and how it gets paid
AvePoint sells data management software: backup, governance, security and migration for data in Microsoft 365, Google and other cloud ecosystems. It calls this the Confidence Platform [1].
Customers pay mostly through SaaS subscriptions. Some still pay for term licenses with support, and AvePoint earns services fees on migrations [1].
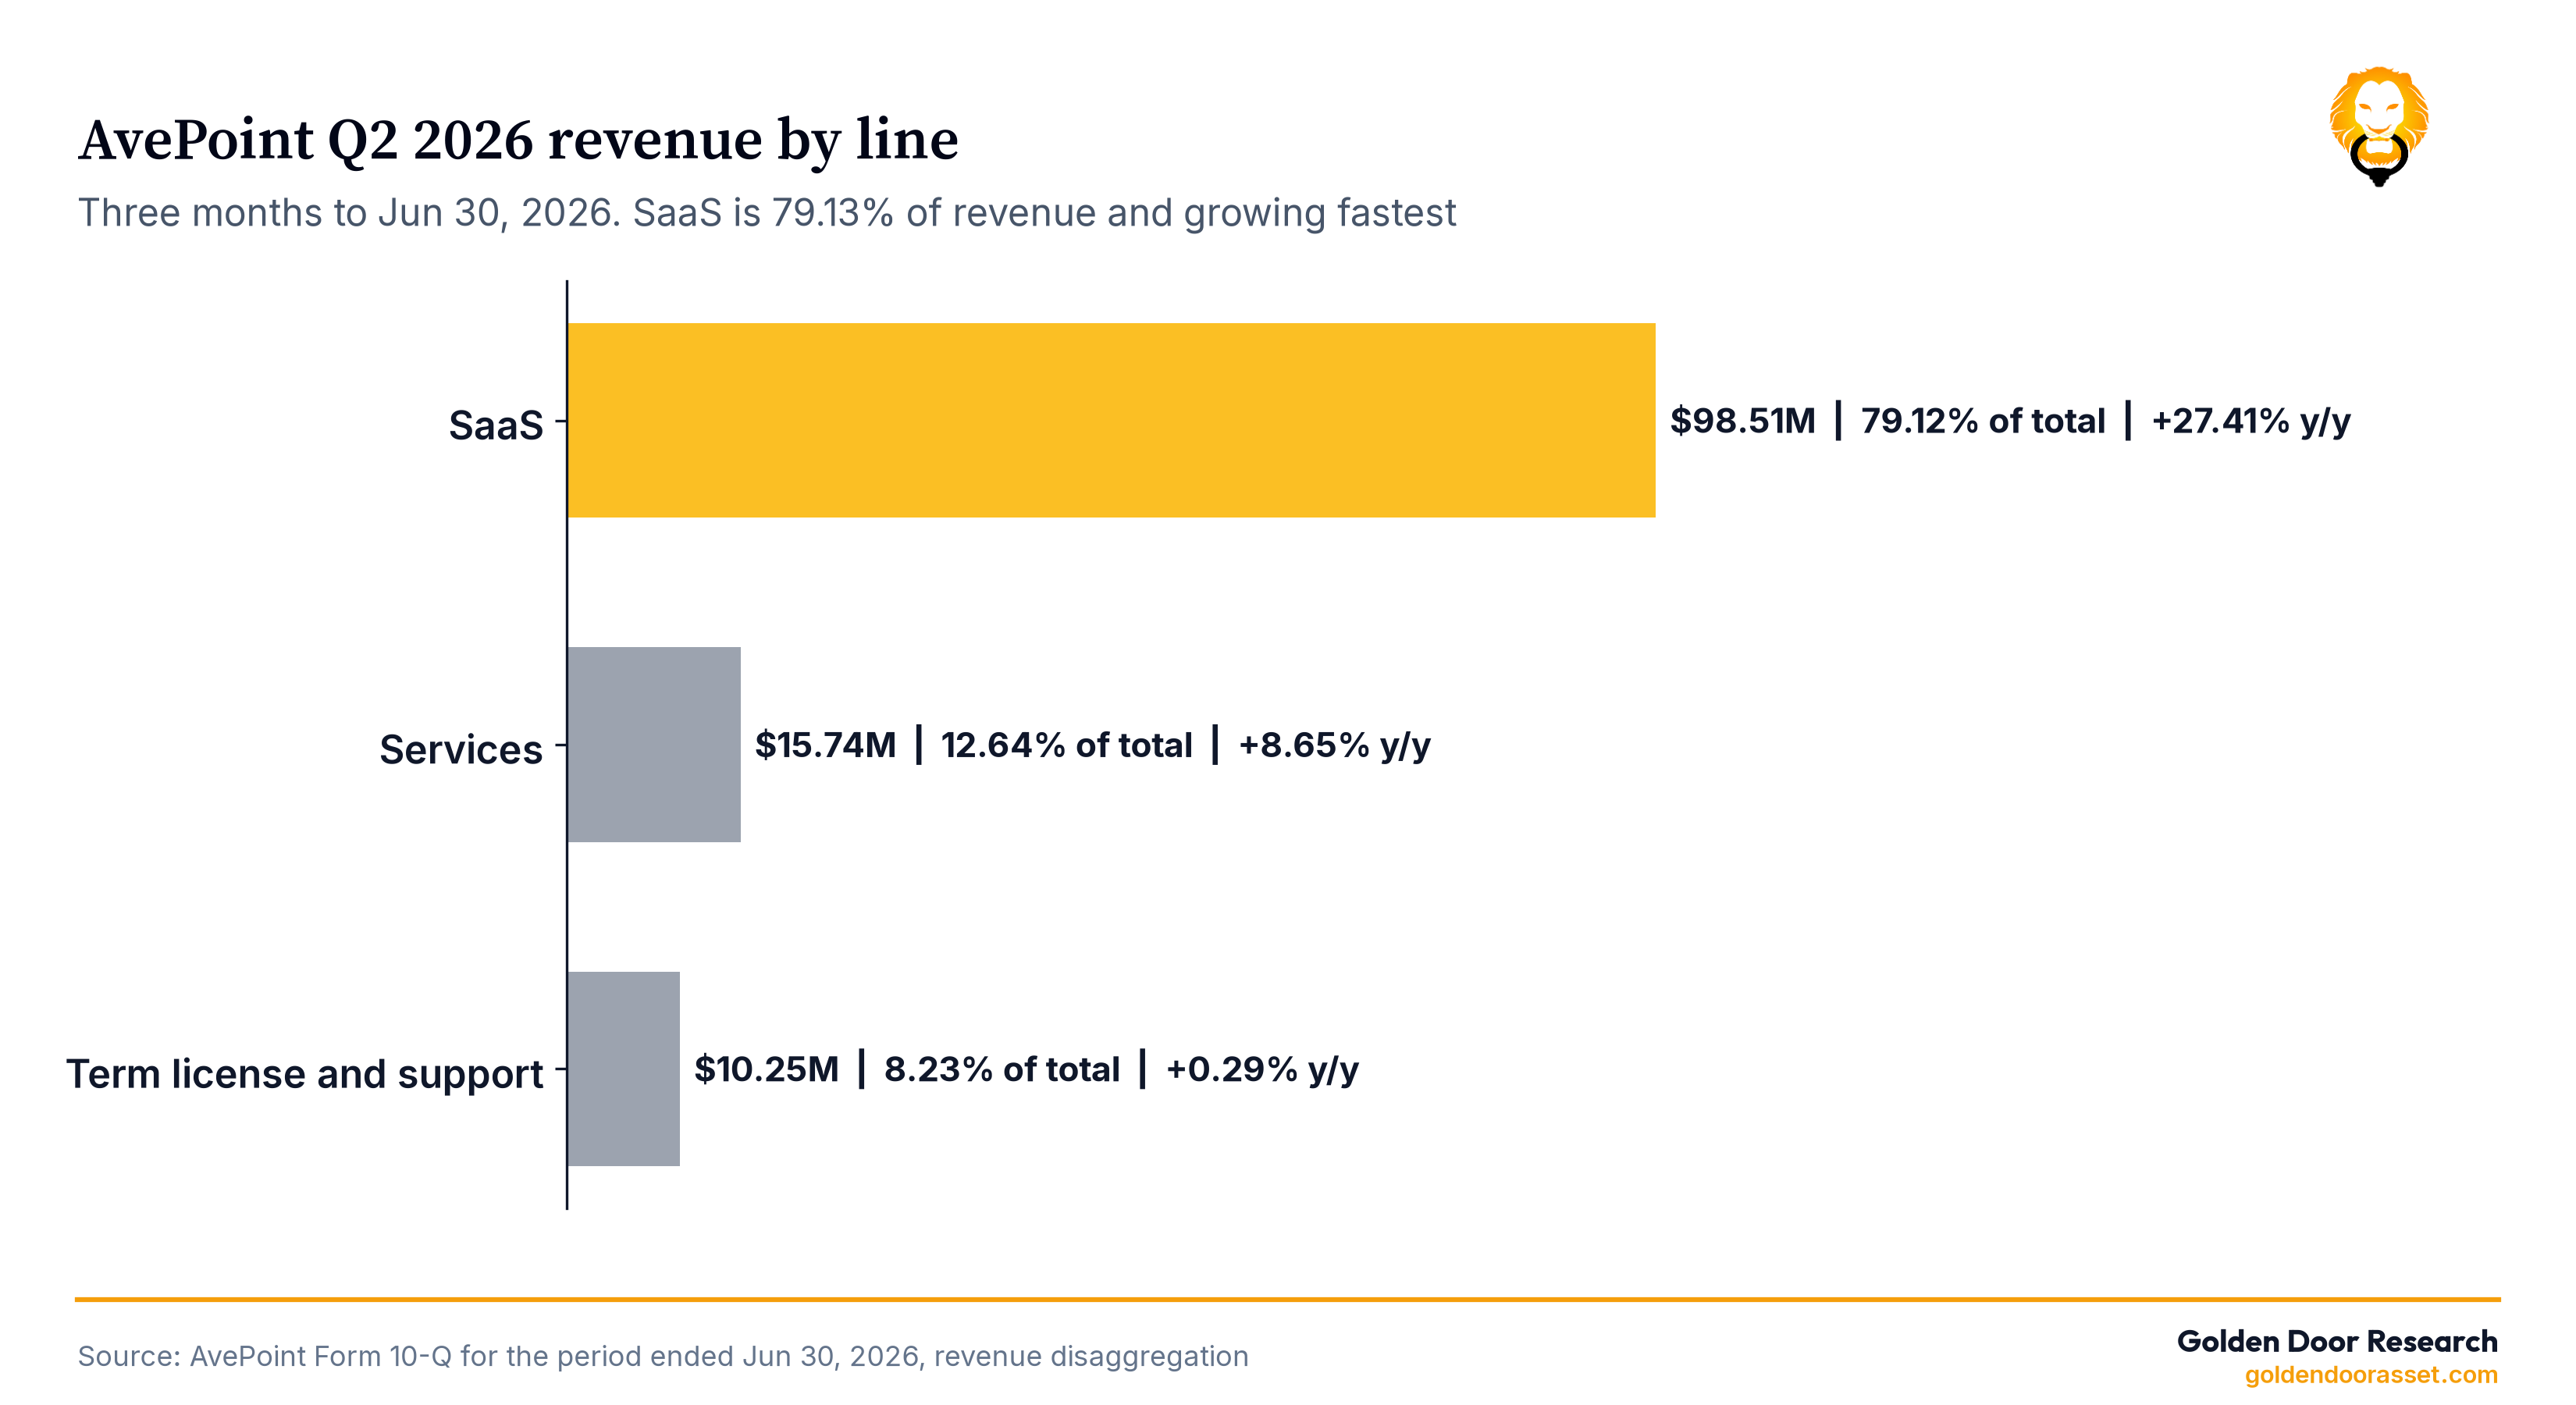
Q2 revenue was $124.50M, up 22.03%. SaaS was $98.51M, up 27.41%.
Term license and support was flat at $10.25M, and services grew 8.65% to $15.74M [1].
Total ARR was $465.1M, up 27%, or 24% adjusted for currency [1]. Remaining performance obligations were $559.4M, with 61% due in twelve months [1].
Growth is broad. North America grew 23.1%, Europe, the Middle East and Africa 26.6% and Asia Pacific 15.9% in Q2 [1].
AvePoint added a secondary listing in Singapore on Sep 18, 2025 [1].
Companies Referenced in This Research
AVPT Stock Profile →Related Coverage & Peer Deep-Dives
View All →Claude Sheets Still Sends Serious Work Back to Excel, but Microsoft's Owner Cash Fell 46.64% in Two Years and Its Market Value Assumes 57% Yearly Growth
Anthropic's new sheets still send serious work back to Excel, but owner cash after capex and stock pay fell 46.64% in two years and the market value assumes about 57% yearly growth. Avoid, conviction 3 of 5.