Golden Door Asset
BenchmarkResearchFinancials
Sign InFull Access

Golden Door Asset

Public software investment firm focused on durable compounders, supported by our software quality ratings and research.

Ratings & Research

  • Research Library
  • R&D Benchmark
  • Methodology
  • Financial Model
  • Investment Mandate
  • Full Access

Company

  • About Us
  • Member Hub
  • Member Sign In
  • Contact Us

Legal

  • Privacy
  • Terms
© 2026 Golden Door Asset. All rights reserved.
Loading equity research...

Golden Door Asset · Investment Committee Research Brief

Intuit Inc.

Published Nov 21, 2026 · Data as of Nov 19, 2026

Research Library/INTUIntuit Inc.
INTU Model →

INTU · Research

Intuit (INTU) Sells Mailchimp to Refocus on the Ledger and the Tax Return

By Vijar Kohli

Intuit (INTU) is selling Mailchimp to Bending Spoons (BSP) so it can win customers from inside the small-business ledger, payroll and the tax return, through what it calls lead to cash. Mailchimp revenue has stalled, down 1.26% in the latest quarter, while the rest of Intuit grew 13% to 17% a year.

72.02·StrongAs of Nov 8, 2026▼ -5.2 YoY#11 RatedResearchPublished Nov 21, 2026 · Data as of Nov 19, 2026· 2 min read · 2 exhibitsUpdated

On Nov 19, 2026, Intuit (INTU) agreed to sell Mailchimp to Bending Spoons (BSP), alongside first-quarter results that cut its fiscal 2027 revenue guide [1][2]. The sale ends the 2021 bet that an email marketing platform would make Intuit the place where small businesses find customers.

Intuit now says it will win customers for its users inside the ledger, through what it calls lead to cash, and will return the cash proceeds through buybacks [2]. What remains is a company built around the small-business ledger, payroll and the tax return, the businesses covered in Intuit Owns the Books and Tax Returns Agents Must Work From.

Exhibit 1Financial Schedule
MetricValuePeriod
Mailchimp revenue$1,268M, down 1.26% in the latest quarterTwelve months to Oct 31, 2026, calculated [3][4]
Mailchimp share of Intuit segment operating income4.1%Twelve months to Oct 31, 2026, calculated [3][4]
Revenue growth without Mailchimp13.26% last quarter, 15.00% last yearQ1 fiscal 2027 and fiscal 2026, calculated [3][4]

Source: Intuit Inc. filings and Golden Door Asset research.
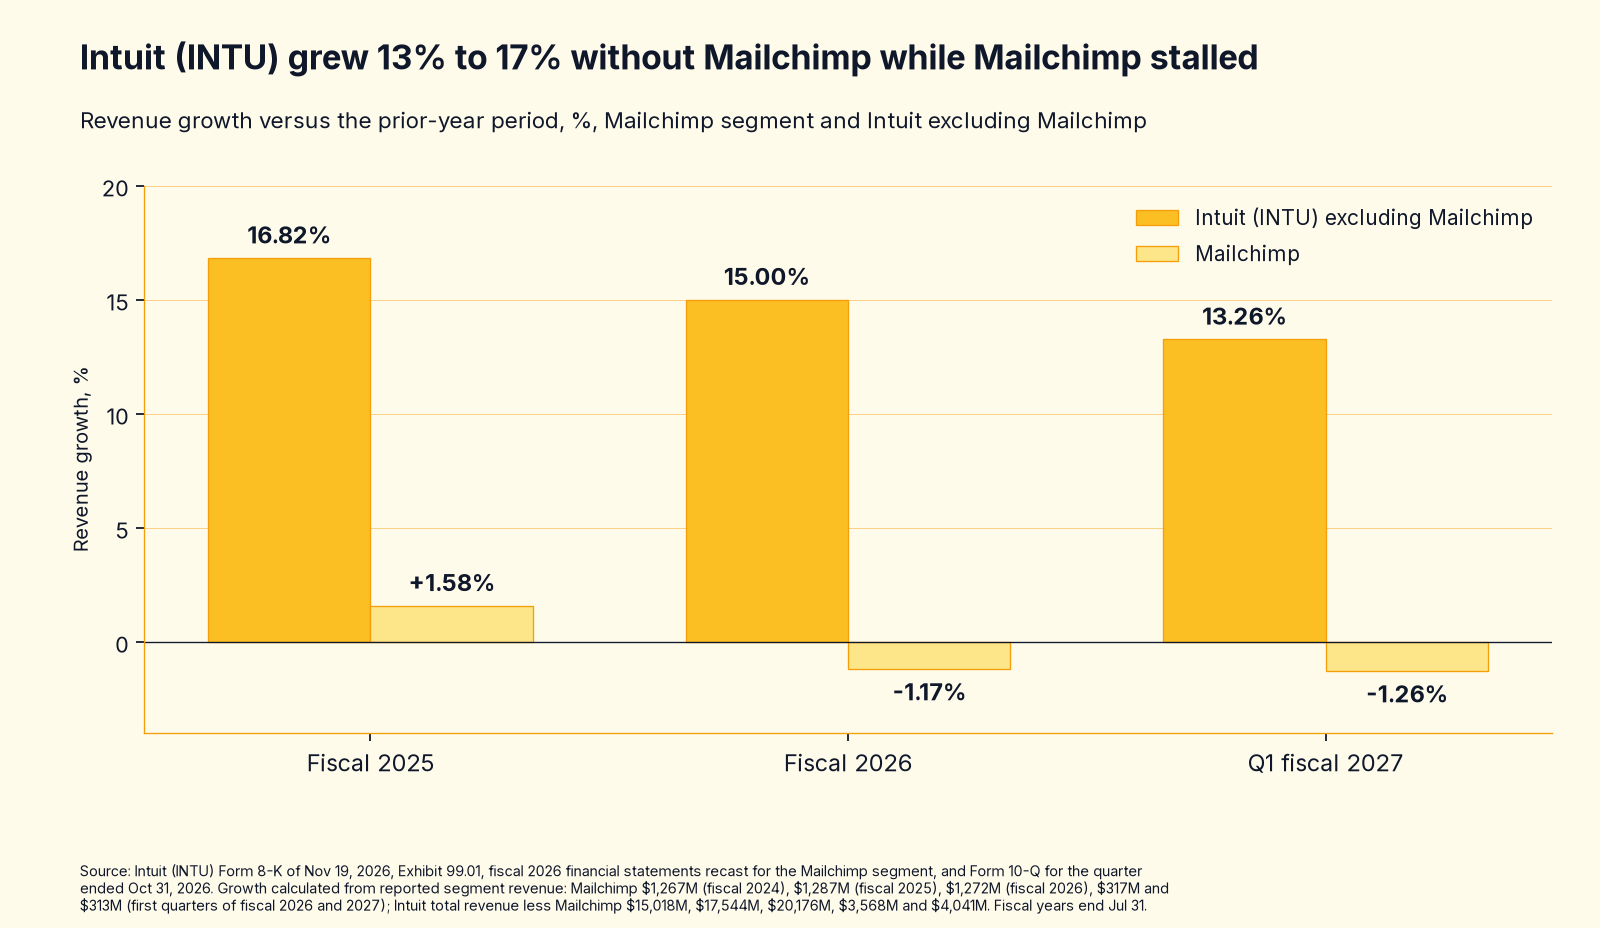
Revenue growth for Intuit (INTU) excluding Mailchimp versus the Mailchimp segment: fiscal 2025 16.82% versus 1.58%, fiscal 2026 15.00% versus -1.17%, first quarter of fiscal 2027 13.26% versus -1.26%.
Exhibit 1. Intuit (INTU) grew 13% to 17% without Mailchimp while Mailchimp stalled.

Intuit (INTU) keeps the job of winning customers, but moves it inside the ledger

Intuit (INTU) gives focus as its reason for the sale. The release says Intuit has built "AI-native experiences to help businesses win new customers, manage their pipeline, and help them grow through its lead to cash capabilities," and that "selling Mailchimp sharpens Intuit's focus behind that strategy" [2].

The 10-Q describes the platform for businesses and accountants as running "from lead to cash", covering financial management, payments and capital, compliance, human capital management and marketing [3].

That is the core of the refocus. Intuit is not leaving customer acquisition to others; it is moving that work next to the invoice, the payment and the books, where the result can be measured in cash collected.

Mailchimp sold sends and contacts to marketers, a market where the buyer can switch tools without moving its accounts. A lead to cash workflow sells the step from a lead to a paid invoice, which runs through the ledger Intuit already holds.

The filings give no revenue or customer count for these native features yet [3][2].

INTU Model

On this page

  1. Intuit (INTU) keeps the job of winning customers, but moves it inside the ledger
  2. Intuit (INTU) agreed a $3.68B base price, with $368M reinvested in Bending Spoons (BSP)
  3. Without Mailchimp, Intuit (INTU) grew 15.00% last year and 13.26% last quarter
  4. Mailchimp was losing paying customers while Intuit (INTU) holds 83% retention in the business group
  5. Most of the $8.32B gap never reached the income statement of Intuit (INTU), so a gain is still expected
  6. Research spending fell to 15.15% of revenue as Intuit (INTU) cut costs and returned cash
  7. Bending Spoons (BSP) runs a price-led harvest that Intuit (INTU) had started but had no reason to finish
  8. General-purpose models press on email marketing while lifting the value of the ledger
  9. Closing terms and the guide cut matter more than the sale price
  10. Goodarzi and Aujla lead Intuit (INTU) through the sale, and no director sits on both boards
  11. Four questions will show whether the refocus pays
Unlock the full note with Full Access

$1,000/yr. The full notes, valuation, exhibits, risks, archive and exports across 130 stocks.

Full Access

Golden Door Membership

Unlock the full institutional underwriting, Bear/Base/Bull valuation cases, exhibits, and permanent research archive across 130 software companies.

Remaining in this report (10 sections)+4 exhibits
  1. 1.Intuit (INTU) agreed a $3.68B base price, with $368M reinvested in Bending Spoons (BSP)
  2. 2.Without Mailchimp, Intuit (INTU) grew 15.00% last year and 13.26% last quarter
  3. 3.Mailchimp was losing paying customers while Intuit (INTU) holds 83% retention in the business group
  4. 4.Most of the $8.32B gap never reached the income statement of Intuit (INTU), so a gain is still expected
  5. 5.Research spending fell to 15.15% of revenue as Intuit (INTU) cut costs and returned cash

Sources

  1. [1]Intuit Inc., Form 8-K, Equity and Asset Purchase Agreement with Bending Spoons US Inc. and Investment Agreement with Bending Spoons S.p.A., Nov 19, 2026.
  2. [2]Intuit Inc., Form 8-K, Exhibit 99.01, first quarter fiscal 2027 results and agreement to sell Mailchimp, Nov 19, 2026.
  3. [3]Intuit Inc., Form 10-Q for the quarter ended Oct 31, 2026, filed Nov 19, 2026.
  4. [4]Intuit Inc., Form 8-K, Exhibit 99.01, fiscal 2026 financial statements recast for the Mailchimp segment, Nov 19, 2026.
  5. [5]Intuit Inc., Form 10-K for the fiscal year ended Jul 31, 2022 (Note 7, Mailchimp purchase price allocation and intangible asset lives).

Company Profile

INTU Stock Profile →
INTUIntuit Inc.

Updates: Intuit Owns the Books and Tax Returns Agents Must Work From, and Its Tax-Adjusted Owner Cash Rose 35% in Two Years

Related Coverage & Peer Deep-Dives

View All →
FICO63.8 · StrongSector Peer
Free summary

Fair Isaac: 51.7% Credit-Scoring Operating Margin

FICO converts $2.53B of FY2026 revenue into a 51.7% GAAP operating margin and $884.5M of owner cash on just $2.1M of capex.

Fair Isaac CorporationNov 8, 2026 · Data as of Sep 30, 2026
DSGX
← All Research LibraryMore INTU Research →
INTU Model →
  • 6.Bending Spoons (BSP) runs a price-led harvest that Intuit (INTU) had started but had no reason to finish
  • 7.General-purpose models press on email marketing while lifting the value of the ledger
  • 8.Closing terms and the guide cut matter more than the sale price
  • 9.Goodarzi and Aujla lead Intuit (INTU) through the sale, and no director sits on both boards
  • 10.Four questions will show whether the refocus pays
  • Locked analytical exhibits (4)

    Owner Cash Waterfall & 5x5 Sensitivity Matrix
    Owner Cash Waterfall
    5x5 Sensitivity Matrix
    Bear/Base/Bull Valuation & RisksAll Exhibits & Financial Schedules130-Stock Archive & CSV Exports
    Get Full Access→
    Instant web & archive accessMember Sign In

    Not ready yet? Get the free opening of each weekly research note by email.

  • [6]Intuit Inc., Form 8-K, Exhibit 99.01, fourth quarter and full year fiscal 2026 results and fiscal 2027 guidance, Aug 25, 2026.
  • [7]QuickBooks blog, "QuickBooks Online August pricing changes and product updates," 2026.
  • [8]Intuit Inc., Form 10-K for the fiscal year ended Jul 31, 2023.
  • [9]Intuit Investor Day, Sep 17, 2026, transcript (Stock Analysis).
  • [10]Intuit Inc., Form 8-K, completion of the Mailchimp acquisition, Nov 1, 2021.
  • [11]Intuit Inc., Form 10-K for the fiscal year ended Jul 31, 2026, filed Sep 9, 2026.
  • [12]Bending Spoons S.p.A., prospectus (Form 424B4), Jul 1, 2026.
  • [13]Bending Spoons S.p.A., Form 6-K, Exhibit 99.1, agreement to acquire Mailchimp, Nov 19, 2026.
  • [14]Bending Spoons S.p.A., Form 6-K, Exhibit 99.1, Q3 2026 results, Nov 19, 2026.
  • [15]Bending Spoons S.p.A., Form 6-K, Exhibit 99.1, $1.3B private placement of ordinary shares, Nov 19, 2026.
  • [16]Bending Spoons S.p.A., Form 6-K, Exhibit 99.1, Berkshire Hathaway's further $330M investment, Oct 29, 2026.
  • [17]Reuters, "Intuit to sell Mailchimp to Bending Spoons for $3.68 billion," Nov 19, 2026, via TradingView.
  • [18]CNBC, "Intuit to sell Mailchimp to Bending Spoons for $3.68 billion," Nov 19, 2026.
  • [19]Intuit Inc., definitive proxy statement for the 2026 annual meeting, filed Nov 26, 2025.
  • [20]Golden Door, "Intuit Owns the Books and Tax Returns Agents Must Work From," Nov 14, 2026.
  • 68.53 · Strong
    Sector Peer
    Free summary

    Descartes Owns the Customs Filing Lane and Spends Nearly All Its Cash Buying More Lanes

    Descartes turns 35% of revenue into owner cash from a freight filing network, but growth from existing customers is under 10% and deals since early 2025 used about all the cash it made.

    The Descartes Systems Group Inc.Nov 1, 2026 · Data as of Oct 31, 2026
    Industry ResearchIndustry Research
    Golden Door

    Clouds Own the Servers. Database Renters Kept the Margin.

    Microsoft (MSFT) and Oracle (ORCL) lost between 2.4 and 9.86 points of cloud margin in their latest quarter as new data center capacity came online, while Snowflake (SNOW), MongoDB (MDB) and Elastic (ESTC) held gross margins of roughly 71% to 77% on infrastructure they rent from those same clouds. Owning servers turns every new data center into depreciation that lands before the revenue does; renting turns it into a usage bill that grows with the customer.

    Golden Door AssetNov 21, 2026 · Data as of Nov 21, 2026
    Industry ResearchIndustry Research
    Golden Door

    Golden Door Asset operates at a 74.1% gross margin on $2.45B revenue

    Golden Door Asset (GDA) earns a "Watch" rating and an institutional Quality Score of 77/100 (Grade A). On $2.45B in baseline revenue (27.3% growth, 74.1% gross margin, 19.9% FCF margin), our 5-year DCF yields an Enterprise Value of $17.70B ($82.94/share vs. $92.76 market price).

    Golden Door AssetNov 21, 2026 · Data as of Oct 1, 2026