Golden Door Asset
BenchmarkResearchFinancials
Sign InFull Access

Golden Door Asset

Public software investment firm focused on durable compounders, supported by our software quality ratings and research.

Ratings & Research

  • Research Library
  • R&D Benchmark
  • Methodology
  • Financial Model
  • Investment Mandate
  • Full Access

Company

  • About Us
  • Member Hub
  • Member Sign In
  • Contact Us

Legal

  • Privacy
  • Terms
© 2026 Golden Door Asset. All rights reserved.
Loading equity research...

Golden Door Asset · Investment Committee Research Brief

ServiceNow

Published Oct 29, 2026 · Data as of Oct 28, 2026

Research Library/NOWServiceNow
NOW Model →

NOW · Research

ServiceNow sells agents by the seat, and customers want it that way

By Vijar Kohli

ServiceNow's third quarter tests a question we parked: will superintelligence agents replace the seats software companies charge for? On this print, no. Agents are adding dollars on top of seats, renewals held at 98%, and the CFO says customers are not asking for outcome pricing.

61.71·StrongAs of Nov 8, 2026▼ -12.1 YoY#34 RatedResearchPublished Oct 29, 2026 · Data as of Oct 28, 2026·
  1. Nov 9, 2026Stamped editorial role: event_update
  1. Nov 9, 2026Stamped editorial role: event_update
· 1 min read · 3 exhibits

ServiceNow's third quarter tests a question we parked: will superintelligence agents replace the seats software companies charge for? On this print, no. Agents are adding dollars on top of seats, renewals held at 98%, and the CFO says customers are not asking for outcome pricing.

The weak spot is the forward guide, not the seat.
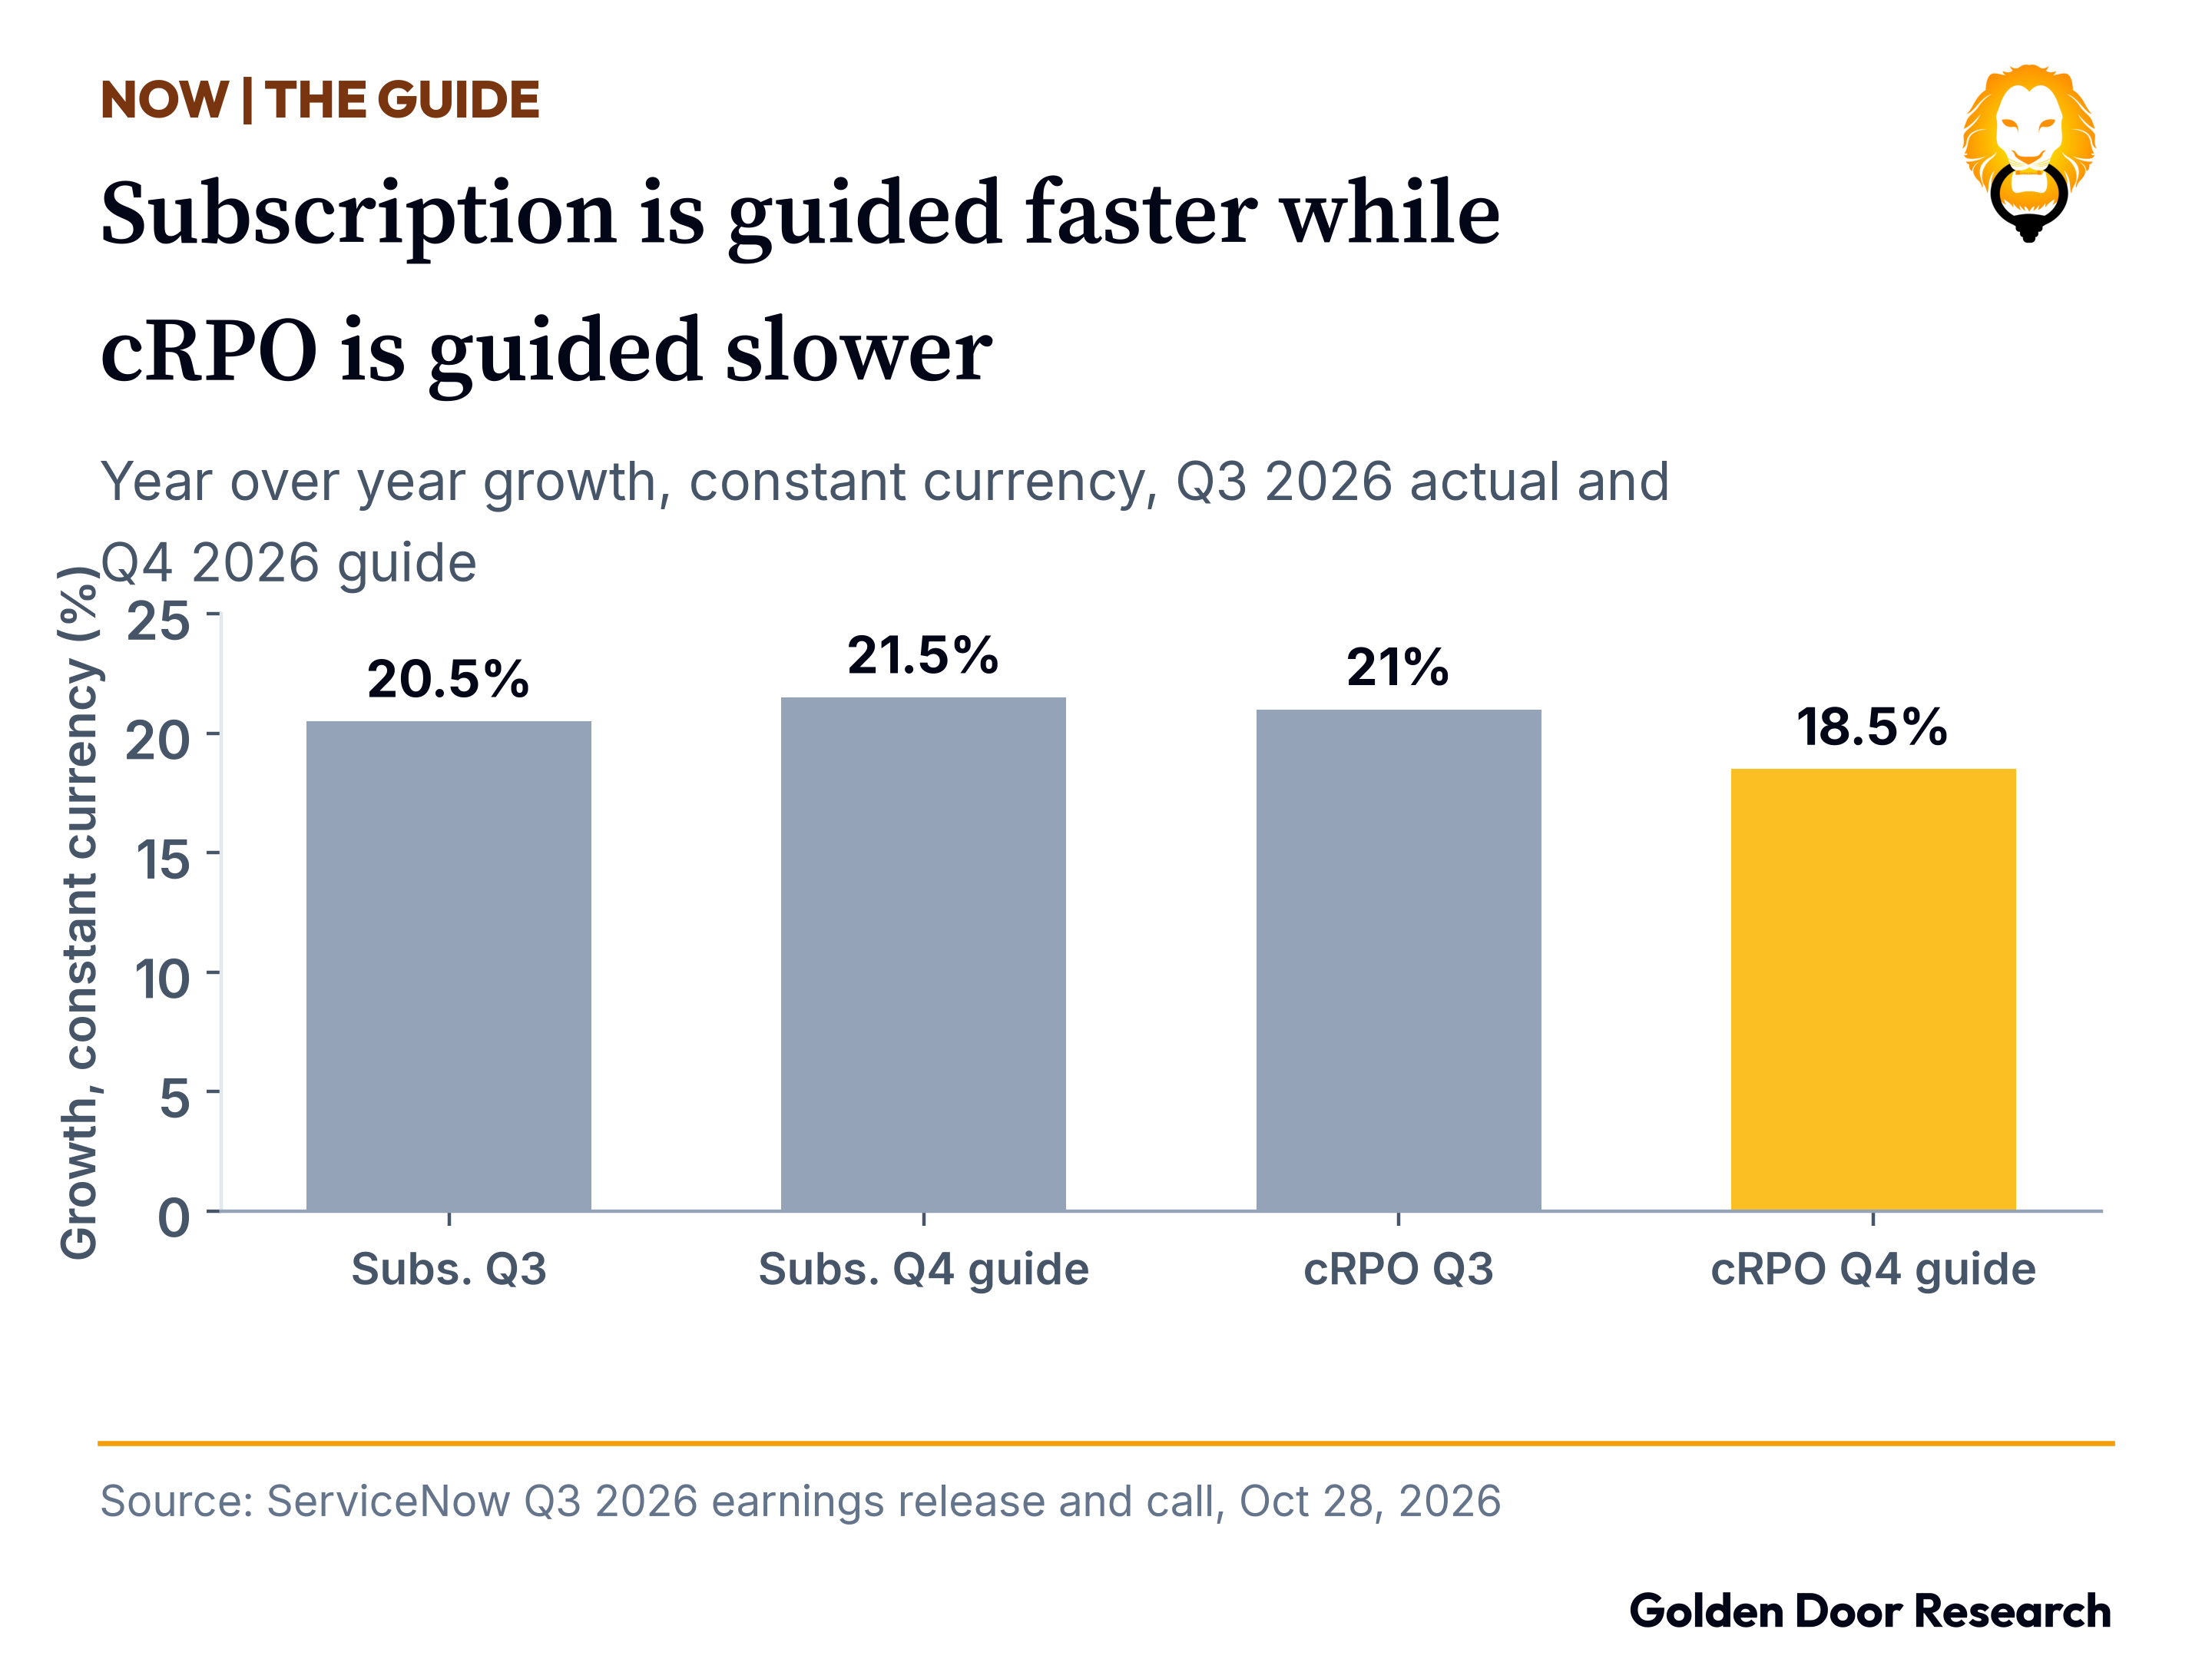
Subscription is guided faster while cRPO is guided slower
Exhibit 2Financial Schedule

Hybrid seat-plus-consumption agent pricing preserves 98% renewals across enterprise workflows

Executive thesis summary, invalidation triggers, and toll-gate read from Q3 2026 results.
ScorecardRead
ThesisServiceNow owns the workflow record, and agents that run through it are priced per seat plus metered use, so the gate charges more per user instead of losing users [1][2]
What proves it wrongThe 10-Q shows falling seat counts or price per seat, or renewals slip below 98%
Gate testOwns the record: yes. Outcome pricing: no, by customer choice [2]

Source: ServiceNow Q3 2026 Form 10-Q and earnings call transcript.

1. What customers are buying

Subscription revenue was $3,988M, up 20.5% in constant currency [1]. Superintelligence net new ACV rose 65%, and the year-end agent ACV target rose to $1.7B from $1.0B at the start of the year [1][2].

CFO Gina Mastantuono said customers prefer the hybrid of seats plus consumption and are "not asking at all for outcome pricing" [2]. Renewal rate held at 98% [2].

In Q2, the CEO said "50% ... of our net new business is already non-seat based" [4]. Q3 did not update that figure.
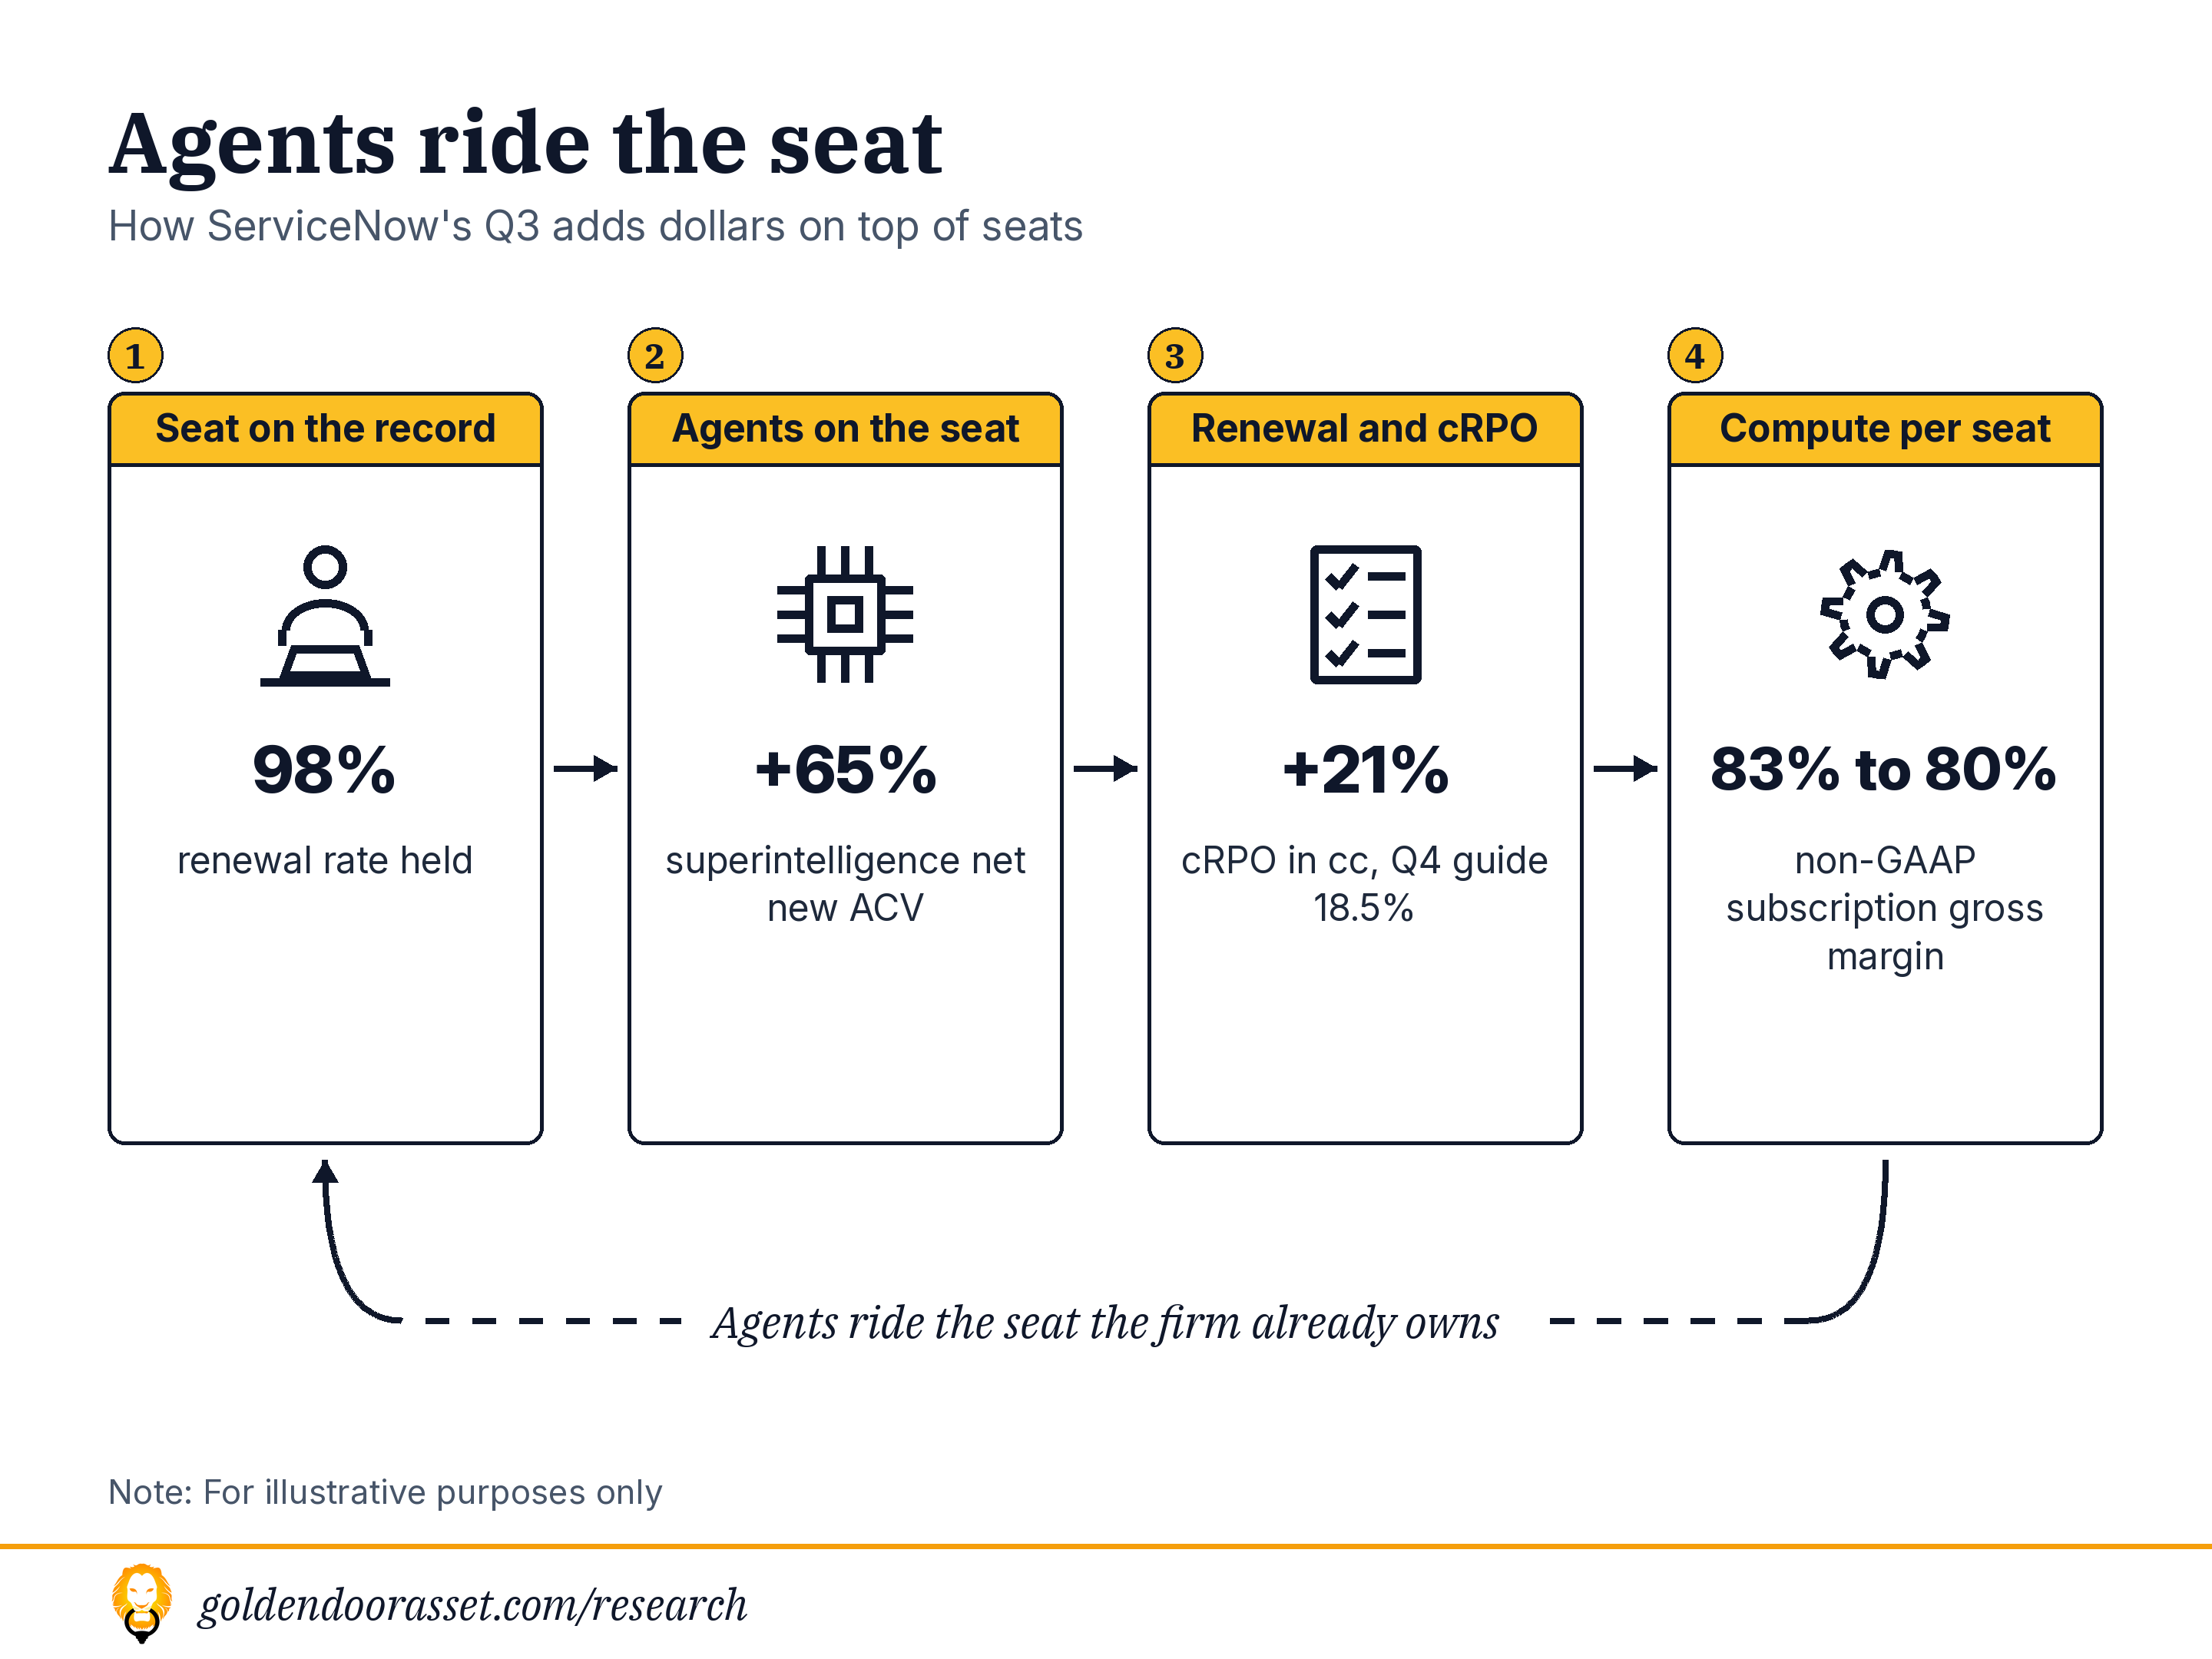
Agents ride the seat, and renewals bring them back

Part of the growth is bought. If Armis added the roughly 175 basis points guided last quarter, organic subscription growth was about 18.75%, our calculation, not a company figure [1][3].

NOW Model

On this page

  1. 1. What customers are buying
  2. 2. Why the guide, not the seat, is the problem
  3. 3. The cost of the lift
  4. What to watch
Unlock the full note with Full Access

$1,000/yr. The full notes, valuation, exhibits, risks, archive and exports across 130 stocks.

Full Access

Golden Door Membership

Unlock the full institutional underwriting, Bear/Base/Bull valuation cases, exhibits, and permanent research archive across 130 software companies.

Remaining in this NOW report (3 sections, ~350 words)+3 exhibits
  1. 1.2. Why the guide, not the seat, is the problem
  2. 2.3. The cost of the lift
  3. 3.What to watch

Locked analytical exhibits (3)

GAAP Net Profit Bridge & 5x5 Sensitivity Matrix

Sources

  1. [1]ServiceNow, Q3 2026 earnings release, Oct 28, 2026
  2. [2]ServiceNow Q3 2026 earnings call transcript, Oct 28, 2026
  3. [3]ServiceNow, Q2 2026 earnings presentation, Armis impact slide
  4. [4]ServiceNow Q2 2026 earnings call transcript
  5. [5]24/7 Wall St., ServiceNow Q3 2026 live coverage, Oct 28, 2026

Company Profile

NOW Stock Profile →
NOWServiceNow, Inc.

Updates: ServiceNow Sells Agents by the Seat, and Stock Pay Rose 28% to Keep Up

Related Coverage & Peer Deep-Dives

View All →
PCTY65.66 · StrongSector Peer
Free summary

$PCTY: Paylocity Keeps the Payroll Record, but Growth Is Slowing and Stock Pay Is Rising Again

Owner cash on the full Golden Door standard was $265.8M over the twelve months to Sep 30, 2026, down from $282.0M in fiscal 2026, as stock pay rose 14.29% in the latest quarter and guidance points to 8% to 9% growth.

Paylocity Holding CorpNov 8, 2026 · Data as of Sep 30, 2026
← All Research LibraryMore NOW Research →
NOW Model →
GAAP Net Profit Bridge
5x5 Sensitivity Matrix
  • Owner cash share of GAAP FCF rose from 36% to 57% over FY2022 to FY2025, though stock pay sti...
  • ServiceNow at $109.67 trades 19% below our $135.49 5-year DCF base fair value
  • ServiceNow 5-year DCF sensitivity: WACC vs. terminal growth
Bear/Base/Bull Valuation & RisksAll Exhibits & Financial Schedules130-Stock Archive & CSV Exports
Get Full Access→
Instant web & archive accessMember Sign In

Not ready yet? Get the free opening of each weekly research note by email.

DUOL75.35 · StrongSector Peer
Free summary

Duolingo: 42.6% Growth and Max Tier Pricing Drive a +31-Point GAAP Margin Swing

Duolingo scaled TTM revenue 42.6% to $1.18B while swinging GAAP operating margin from -17.6% in FY2022 to +13.7% TTM ($407.0M GAAP FCF).

Duolingo, Inc.Nov 8, 2026 · Data as of Sep 30, 2026
PAYC76.98 · StrongSector Peer
Free summary

Paycom: Beti Self-Service Payroll Re-Accelerates With 30.3% GAAP Operating Margin

Paycom pairs 83.7% gross margin, 30.3% GAAP operating margin, and $580.2M of TTM owner cash with an 18.1% revenue rebound.

Paycom Software, Inc.Nov 8, 2026 · Data as of Sep 30, 2026
Industry ResearchIndustry Research
Golden Door

Clouds Own the Servers. Database Renters Kept the Margin.

Microsoft (MSFT) and Oracle (ORCL) lost between 2.4 and 9.86 points of cloud margin in their latest quarter as new data center capacity came online, while Snowflake (SNOW), MongoDB (MDB) and Elastic (ESTC) held gross margins of roughly 71% to 77% on infrastructure they rent from those same clouds. Owning servers turns every new data center into depreciation that lands before the revenue does; renting turns it into a usage bill that grows with the customer.

Golden Door AssetNov 21, 2026 · Data as of Nov 21, 2026