
Golden Door Asset · Investment Committee Research Brief
OneSpan Inc.
Published Oct 31, 2026 · Data as of Oct 31, 2026
OSPN · Research
OneSpan's 12% Quarter Was 8% Without Upfront Licenses. Its E-Signature Unit Is the Part Compounding
Multi-year licenses booked upfront added $2.3M to OneSpan's third quarter. Underneath, the authentication business lost profit this year while Digital Agreements lifted operating income 84.5% to $19.2M in nine months.
Full Research & Archive: Ratings and research summaries stay free for everyone. Full Access unlocks the full research reports, the archive and the CSV export across 100+ software companies.
Explore Full Access →Reverse-DCF Valuation Expectations Gap
Aligned With Fundamentals5-year unlevered DCF revenue CAGR hurdle implied by OneSpan Inc. (OSPN) current enterprise value ($843M) at 3.0% terminal growth, compared against reported trailing YoY revenue growth and 1-year R&D payback.
- Implied 5Y CAGR Hurdle
- 1.3%
- Reported YoY Revenue Growth
- 3.2%
- Expectations Spread
- -1.9 pp
- Q3 revenue growth without the multi-year license pull-forward
- 7.9%
- Digital Agreements operating income growth
- 84.5%
- Owner cash
- $32.1M
$63.9M
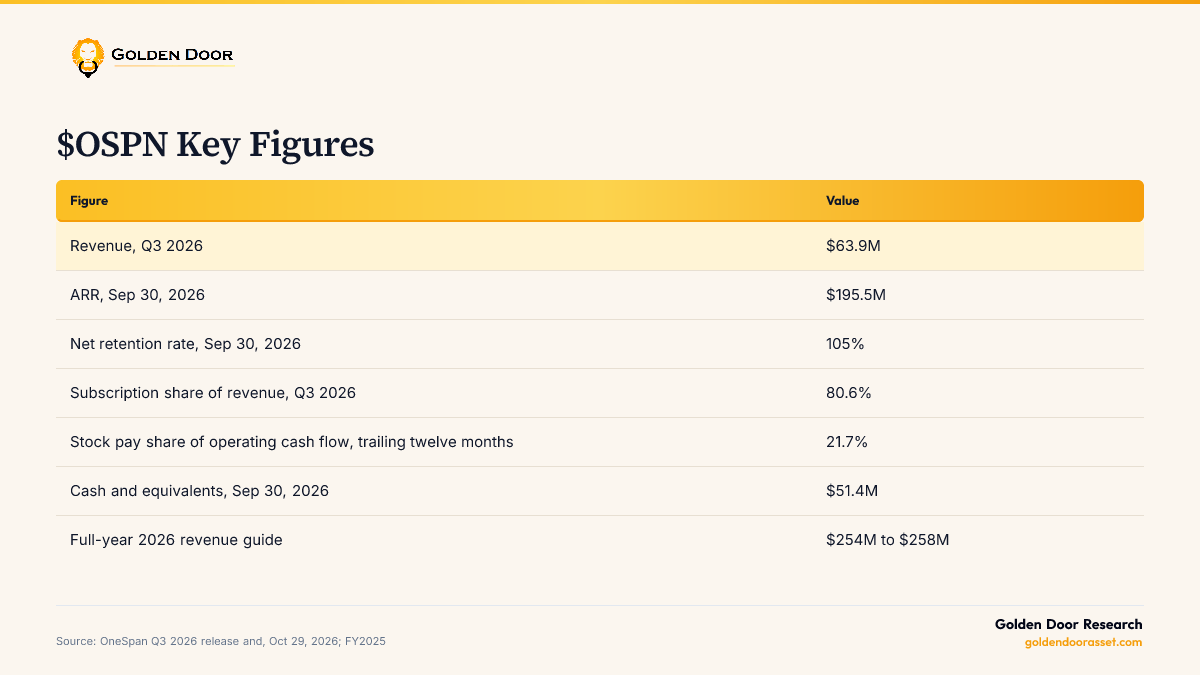
| Figure | Value |
|---|---|
| Revenue, Q3 2026 | $63.9M |
| ARR, Sep 30, 2026 | $195.5M |
| Net retention rate, Sep 30, 2026 | 105% |
| Subscription share of revenue, Q3 2026 | 80.6% |
| Stock pay share of operating cash flow, trailing twelve months | 21.7% |
| Cash and equivalents, Sep 30, 2026 | $51.4M |
| Full-year 2026 revenue guide | $254M to $258M |
Source: OneSpan Q3 2026 release and, Oct 29, 2026; FY2025
Golden Door Researchgoldendoorasset.com
$OSPN key figures, latest filings.
1. Verdict and what this piece answers
Verdict: Hold off, conviction 3 of 5. The anchor is trailing twelve-month owner cash of $32.1M, meaning operating cash flow less all capex less stock pay, our calculation [1][3]. We set no base value: owner cash was negative $37.6M in fiscal 2023, so OneSpan has only two positive full years [3].
OneSpan printed third-quarter 2026 revenue of $63.9M, up 12%, raised its full-year revenue guide to $254M to $258M from $248M to $252M, and lifted its Adjusted EBITDA guide to $72M to $76M [2]. The headline reads like a turnaround that has become a growth story.
This piece asks two narrower questions. How much of that 12% will repeat?
And which half of the company is actually compounding?
The answers point in opposite directions. The 10-Q says customers moving from single-year to multi-year on-premises term licenses added $2.3M of revenue in the quarter, because OneSpan books that license revenue upfront [1].
Take it out and the quarter grew 7.9%, our calculation, which sits close to annual recurring revenue growth of 9% [1]. Meanwhile the smaller business the market tends to ignore, Digital Agreements, the e-signature unit built around OneSpan Sign, lifted its nine-month operating income 84.5% to $19.2M on 17% revenue growth [1].
Our view: the market is pricing OneSpan as one slow security vendor with a hardware tail. It is really a steady authentication franchise whose profit fell this year, paired with an e-signature business whose profit nearly doubled.
Company Profile
OSPN Stock Profile →Related Coverage & Peer Deep-Dives
View All →Qualys Bought Back More Stock Than It Kept in Owner Cash as Growth Settled Near 10 Percent
Qualys turns a third of revenue into owner cash, but since 2020 buybacks topped that cash while existing customers expanded spending by only 3% a year.