Golden Door Asset
BenchmarkResearchFinancials
Sign InFull Access

Golden Door Asset

Public software investment firm focused on durable compounders, supported by our software quality ratings and research.

Ratings & Research

  • Research Library
  • R&D Benchmark
  • Methodology
  • Financial Model
  • Investment Mandate
  • Full Access

Company

  • About Us
  • Member Hub
  • Member Sign In
  • Contact Us

Legal

  • Privacy
  • Terms
© 2026 Golden Door Asset. All rights reserved.
Loading equity research...

Golden Door Asset · Investment Committee Research Brief

monday.com Ltd.

Published Oct 24, 2026 · Data as of Sep 30, 2026

Research Library/MNDYmonday.com Ltd.
MNDY Model →

MNDY · Research

monday.com's Agent Meter Is Real but Small, and Owner Cash After Stock Pay Has Been Positive in Only Two of Four Periods

By Vijar Kohli

monday.com now discloses $36M of superintelligence ARR, led by credits, but the self-serve funnel added only 182 customers above 10 users, retention slipped to 108%, and owner cash after stock pay was positive in only two of four periods.

75.58·StrongAs of Nov 8, 2026▼ -4.4 YoY#5 RatedResearchPublished Oct 24, 2026 · Data as of Sep 30, 2026·
  1. Nov 20, 2026Compliance hygiene: removed Buy/Hold/Sell verdict framing
  2. Nov 14, 2026Updated Nov 14, 2026: rolled to the Sep 30, 2026 quarter; added superintelligence ARR, the May 6 pricing carve-out, the July restructuring cash, the case against, a valuation on market value with a reverse DCF, and a call of Hold off, conviction 3 of 5.
  1. Nov 20, 2026Compliance hygiene: removed Buy/Hold/Sell verdict framing
  2. Nov 14, 2026Updated Nov 14, 2026: rolled to the Sep 30, 2026 quarter; added superintelligence ARR, the May 6 pricing carve-out, the July restructuring cash, the case against, a valuation on market value with a reverse DCF, and a call of Hold off, conviction 3 of 5.
· 1 min read · 3 exhibits

Executive Thesis & Key Numbers

TTM Owner Cash
-$6.07M

TTM Sep 30

+$41.12M ex-restruct

Superintelligence ARR
$36M

2.38% of Q3 ann.

Credits-led

10+ User Net Adds
+182

To 65,965

NDR 108% -> 107%

Market Value / Implied
$3,412.66M

Q3 ann. $91.83M

14.43% 5Y CAGR

Investment Thesis

monday.com disclosed $36M of superintelligence ARR (2.38% of annualized Q3 revenue) led by credits, yet net adds above 10 users slowed to +182, NDR slipped to 108% (guided to 107%), and owner cash after stock pay was positive in only 2 of 4 periods (-$6.07M TTM). No base value can be set, while Q3 annualized post-restructuring cash ($91.83M) implies 14.43% 5Y growth near the ~14% Q4 revenue guide.

Updated Nov 14, 2026: rolled to the quarter ended Sep 30, 2026, added the first dollar figure for superintelligence ARR, the May 6 seats-plus-credits carve-out, the July restructuring and its cash, the case against, a valuation on the Nov 13, 2026 market value with a reverse DCF, and a call. The earlier version set no call.

MNDY Model

On this page

  1. Executive Thesis & Key Numbers
  2. 1. Call: Hold off, conviction 3 of 5, a meter worth watching on a cash record too short to value
  3. 2. Research spending is a quarter of revenue, the API is first rate, and GAAP profit is thin
  4. 3. Growth is stepping down from 27% to about 14%
  5. 4. Agents, voice and engineers shipped fast, and none has its own revenue line yet
  6. 5. Retention is slipping overall and holding in large accounts
  7. 6. Adjusted free cash flow was $63.00M, and owner cash after stock pay was below zero
  8. 7. One small acquisition, for voice
  9. 8. Risks and catalysts
  10. 8b. The case against, scored
  11. 9. Valuation: no base value, and the market needs a recovery the record has not yet shown
  12. The Bull Case vs. The Bear Case on monday.com
  13. 10. Superintelligence angle: mixed
  14. 11. Founders run the company, and one founder share carries a veto
  15. 12. Questions for management, and the predictions being tracked
  16. Bottom line: a credible meter on an unproven cash record
Unlock the full note with Full Access

$1,000/yr. The full notes, valuation, exhibits, risks, archive and exports across 130 stocks.

Full Access

Golden Door Membership

Unlock the full institutional underwriting, Bear/Base/Bull valuation cases, exhibits, and permanent research archive across 130 software companies.

Remaining in this MNDY report (15 sections, ~3,350 words)+11 exhibits
  1. 1.1. Call: Hold off, conviction 3 of 5, a meter worth watching on a cash record too short to value
  2. 2.2. Research spending is a quarter of revenue, the API is first rate, and GAAP profit is thin
  3. 3.3. Growth is stepping down from 27% to about 14%
  4. 4.4. Agents, voice and engineers shipped fast, and none has its own revenue line yet
  5. 5.5. Retention is slipping overall and holding in large accounts

Sources

  1. [1]monday.com Ltd., Form 20-F for the fiscal year ended Dec 31, 2025, filed Mar 13, 2026.
  2. [2]monday.com Ltd., Form 6-K Exhibit 99.1, third quarter 2026 results, furnished Nov 9, 2026.
  3. [3]monday.com, Q3 2026 Shareholder Letter, Nov 9, 2026.
  4. [4]monday.com, Q3 2026 Investor Slides, Nov 9, 2026.
  5. [5]monday.com Ltd., Form 6-K, restructuring plan, furnished Jul 22, 2026.
  6. [6]

Companies Referenced in This Research

MNDY Stock Profile →
MNDYmonday.com Ltd.CRMSalesforce, Inc.

Related Coverage & Peer Deep-Dives

View All →
PCTY65.66 · StrongSector Peer
Free summary

$PCTY: Paylocity Keeps the Payroll Record, but Growth Is Slowing and Stock Pay Is Rising Again

Owner cash on the full Golden Door standard was $265.8M over the twelve months to Sep 30, 2026, down from $282.0M in fiscal 2026, as stock pay rose 14.29% in the latest quarter and guidance points to 8% to 9% growth.

Paylocity Holding CorpNov 8, 2026 · Data as of Sep 30, 2026
← All Research LibraryMore MNDY Research →
MNDY Model →

The central test is whether May 6 seats-plus-credits pricing can offset a shrinking search-fed self-serve funnel while stock pay ($140.25M TTM, 58.41% of operating cash flow) still absorbs reported free cash flow [1][2]. Because CRM, dev, and service sit outside the credits model at 11.7% of ARR (+10 bps QoQ), the meter remains too small to carry a Buy without three consecutive positive owner-cash years [3][8].

Exhibit 1Financial Schedule
MetricValuePeriod
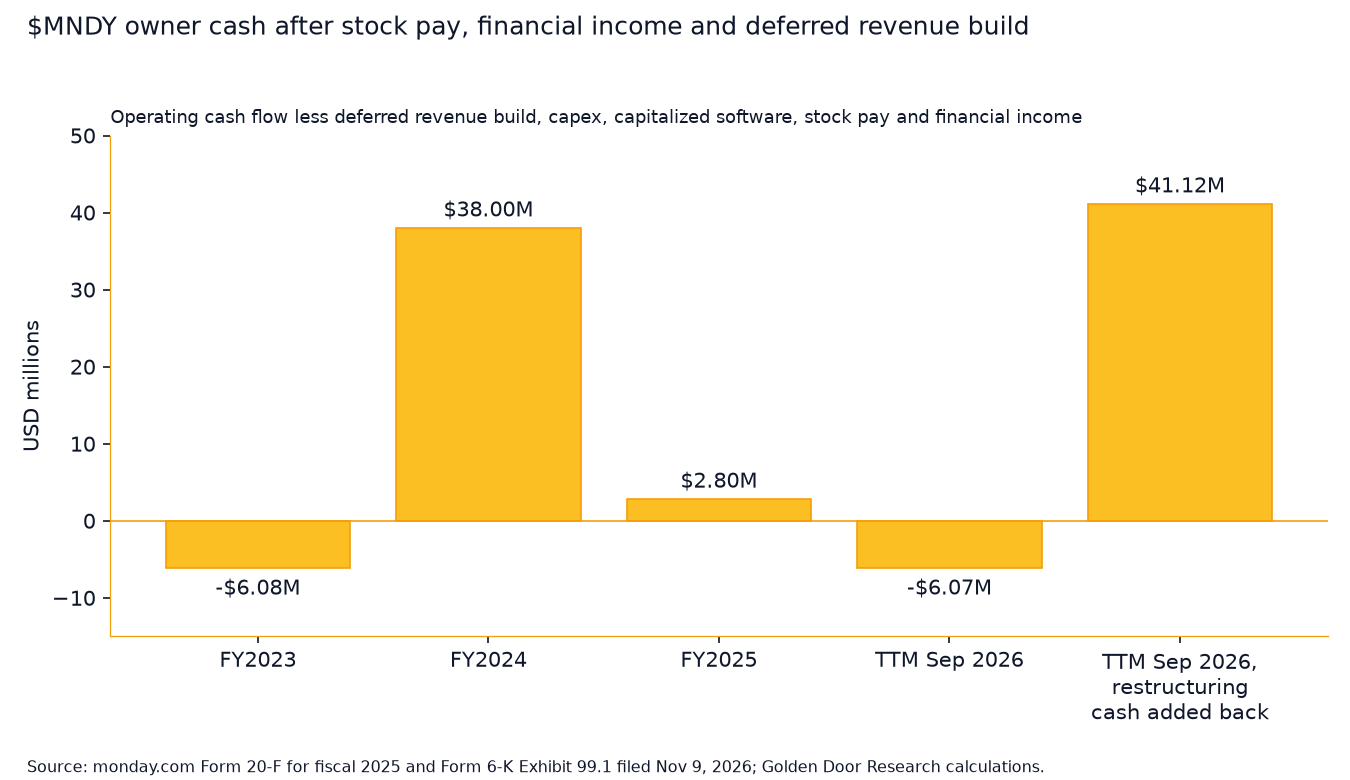
Owner cash after stock pay, financial income and deferred revenue build-$6.07MTwelve months to Sep 30, 2026, calculated
Same, with the $47.19M of restructuring cash added back$41.12MTwelve months to Sep 30, 2026, calculated
Superintelligence ARR (company "AI ARR")$36M, 2.38% of annualized quarterly revenueSep 30, 2026, ratio calculated
Customers with more than 10 users, sequential change+182, to 65,965Jun 30 to Sep 30, 2026, calculated

Source: monday.com Ltd. filings and Golden Door Asset research.

Exhibit 2Data Exhibit

Exhibit 1A: $MNDY Economic Owner Cash Trajectory (FY2023 to TTM Sep 30, 2026, $M)

Operating cash flow less deferred revenue build, capex, capitalized software, stock pay, and financial income.
FY2023
-$6.08
FY2024
$38
FY2025
$2.8
TTM Sep 30
-$6.07
TTM ex-Restruct
$41.12

Source: monday.com Form 20-F and Form 6-K filings [1][2].

$MNDY owner cash after stock pay, financial income and deferred revenue build, fiscal 2023 to the twelve months to Sep 30, 2026
Chart: $MNDY owner cash after stock pay, financial income and deferred revenue build, fiscal 2023 to the twelve months to Sep 30, 2026.
6.
6. Adjusted free cash flow was $63.00M, and owner cash after stock pay was below zero
  • 7.7. One small acquisition, for voice
  • 8.8. Risks and catalysts
  • 9.8b. The case against, scored
  • 10.9. Valuation: no base value, and the market needs a recovery the record has not yet shown
  • 11.The Bull Case vs. The Bear Case on monday.com
  • 12.10. Superintelligence angle: mixed
  • 13.11. Founders run the company, and one founder share carries a veto
  • 14.12. Questions for management, and the predictions being tracked
  • 15.Bottom line: a credible meter on an unproven cash record
  • Locked analytical exhibits (11)

    GAAP Net Profit Bridge & 5x5 Sensitivity Matrix
    GAAP Net Profit Bridge
    5x5 Sensitivity Matrix
    • Exhibit 5A: $MNDY Toll-Gate & Product-Line Economics Matrix
    • Exhibit 6A: TTM Sep 30, 2026 GAAP Operating Cash Flow to Economic Owner Cash ($M)
    • Exhibit 6B: Work-Management & Enterprise SaaS Peer Benchmark (R&D Payback vs. Growth)
    • Exhibit 9A: Implied Equity Value Range on Q3 Post-Restructuring Cash ($M)
    Bear/Base/Bull Valuation & RisksAll Exhibits & Financial Schedules130-Stock Archive & CSV Exports
    Get Full Access→
    Instant web & archive accessMember Sign In

    Not ready yet? Get the free opening of each weekly research note by email.

    monday.com Ltd., Form 6-K Exhibit 99.1, second quarter 2026 results, furnished Aug 10, 2026, and the Q2 2026 Shareholder Letter.
  • [7]Transcript of the monday.com Q3 2026 earnings call, Nov 9, 2026, The Motley Fool, from the official webcast.
  • [8]monday.com support, "The pricing model for monday AI portfolio," last modified Oct 2, 2026.
  • [9]monday.com developer documentation: authentication, rate limits, changelog, Platform MCP and apps SDKs, retrieved Nov 11 and Nov 14, 2026.
  • [10]monday.com pricing page, retrieved Nov 11, 2026.
  • [11]Nasdaq, MNDY historical quotes, close of Nov 13, 2026, retrieved Nov 14, 2026.
  • DUOL75.35 · StrongSector Peer
    Free summary

    Duolingo: 42.6% Growth and Max Tier Pricing Drive a +31-Point GAAP Margin Swing

    Duolingo scaled TTM revenue 42.6% to $1.18B while swinging GAAP operating margin from -17.6% in FY2022 to +13.7% TTM ($407.0M GAAP FCF).

    Duolingo, Inc.Nov 8, 2026 · Data as of Sep 30, 2026
    PAYC76.98 · StrongSector Peer
    Free summary

    Paycom: Beti Self-Service Payroll Re-Accelerates With 30.3% GAAP Operating Margin

    Paycom pairs 83.7% gross margin, 30.3% GAAP operating margin, and $580.2M of TTM owner cash with an 18.1% revenue rebound.

    Paycom Software, Inc.Nov 8, 2026 · Data as of Sep 30, 2026
    Industry ResearchIndustry Research
    Golden Door

    Clouds Own the Servers. Database Renters Kept the Margin.

    Microsoft (MSFT) and Oracle (ORCL) lost between 2.4 and 9.86 points of cloud margin in their latest quarter as new data center capacity came online, while Snowflake (SNOW), MongoDB (MDB) and Elastic (ESTC) held gross margins of roughly 71% to 77% on infrastructure they rent from those same clouds. Owning servers turns every new data center into depreciation that lands before the revenue does; renting turns it into a usage bill that grows with the customer.

    Golden Door AssetNov 21, 2026 · Data as of Nov 21, 2026