
MSFT · Research
Claude Sheets Still Sends Serious Work Back to Excel, but Microsoft's Owner Cash Fell 46.64% in Two Years and Its Market Value Assumes 57% Yearly Growth
Anthropic's new sheets still send serious work back to Excel, but owner cash after capex and stock pay fell 46.64% in two years and the market value assumes about 57% yearly growth. Avoid, conviction 3 of 5.
Full Research & Archive: Ratings and research summaries stay free for everyone. Full Access unlocks the full research reports, the archive and the CSV export across 100+ software companies.
Explore Full Access →New research, Nov 14, 2026. It tests whether the Office toll gate holds after Anthropic's Nov 10, 2026 launch of Claude Sheets, Whiteboards and Data, and values the whole company on owner cash after stock pay. It does not replace the Oct 26, 2026 piece on capex or the Oct 29, 2026 piece on OpenAI.
Call: Avoid, conviction 3 of 5.
| Metric | Value | Period |
|---|---|---|
| Owner cash after stock pay, deferred revenue build, interest income and tax timing | $31,563.27M | Fiscal year ended Jun 30, 2026, calculated |
| Same measure | $59,156.56M | Fiscal 2024, calculated |
| Cash capex as a share of operating cash flow | 63.4% | Fiscal 2026, calculated |
| Microsoft 365 commercial seat growth | 5% | Quarter ended Sep 30, 2026 |
Source: Microsoft Corporation filings and Golden Door Asset research.
1. Call: Avoid, conviction 3 of 5, a toll gate that holds, priced for growth owner cash has not shown
Call: Avoid. The Office toll gate holds on the product facts.
When Anthropic launched Claude Sheets and Whiteboards in beta and made Claude Data generally available on Nov 10, 2026, its own article said sheets offer "simple spreadsheet functionality" for now, and that users who need "the full functionality of Excel" can export to .xlsx or CSV or use Claude for Excel [8]. Claude for Excel is an add-in deployed through AppSource and the Microsoft 365 Admin Center, and it does not support data tables, macros or VBA [9].
The most capable spreadsheet work still lands in Excel, inside Microsoft 365, on Microsoft's plane.
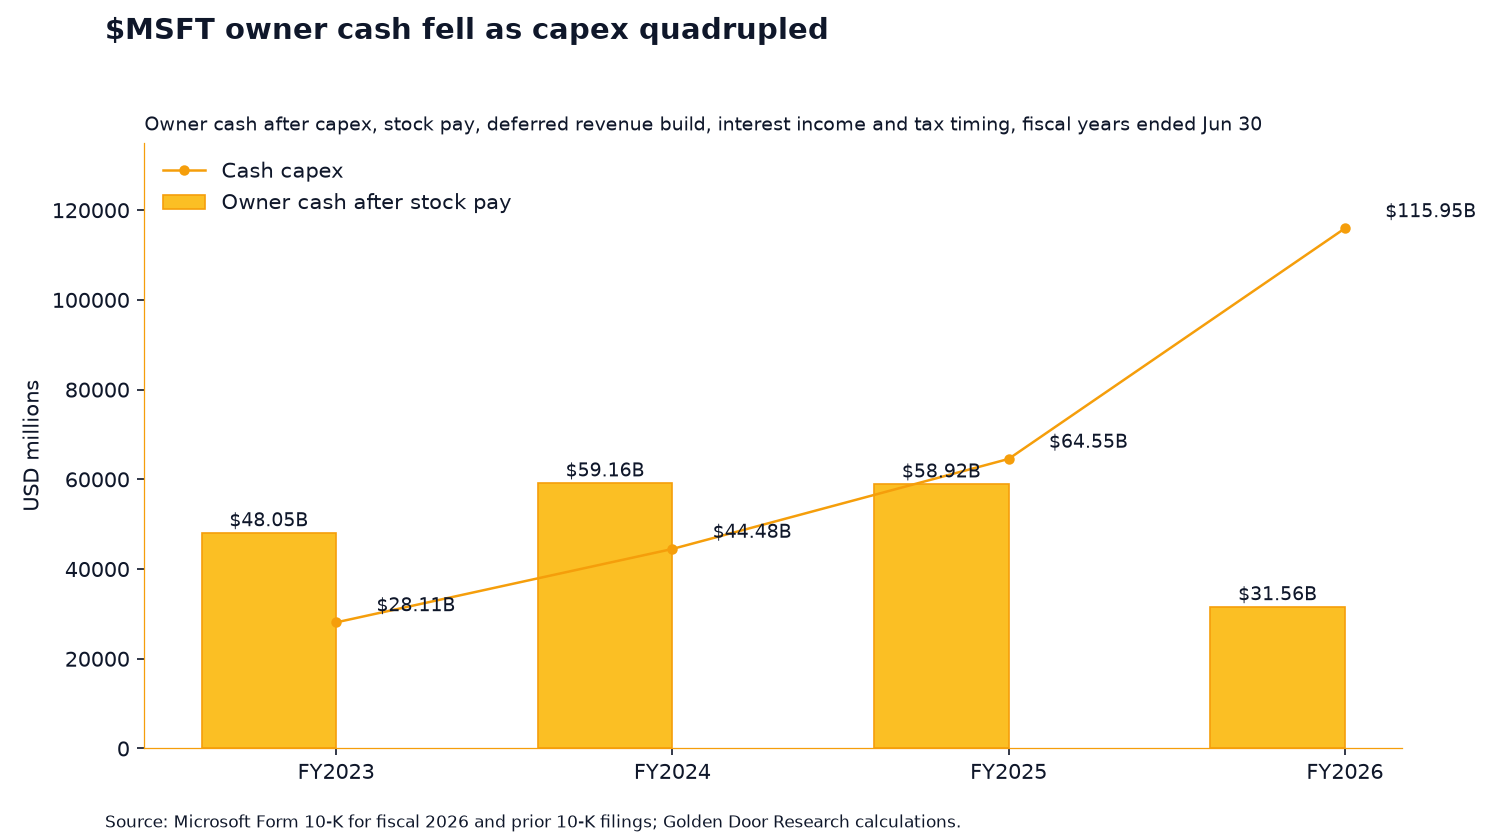
The price is the problem. Owner cash, meaning operating cash flow less the deferred revenue build, capex, stock pay, after-tax interest and dividend income, and the gap between tax expense and cash taxes, was $31,563.27M in fiscal 2026, down 46.64% from $59,156.56M in fiscal 2024, calculated [1].
Cash capex took 63.38% of operating cash flow in fiscal 2026 and 67.87% in the September quarter, calculated [1][2]. At the Nov 13, 2026 close, the market value of $3,890,434.80M implies owner cash growth of 57.08% a year for five years at a 9% discount rate, calculated [2][11].
The base value of $655,758.72M is 83.14% below market value; even with capex reset to its fiscal 2024 share of revenue, the base would be 52.69% below (section 9).
Conviction is 3 of 5. Quality is clear; the price is wrong on this standard. The standard values a build phase on its lowest owner cash, and Azure grew 48% to $33,165M while commercial remaining performance obligation reached $677B, up 73%, so part of today's capex should earn returns the anchor does not yet show [2][3].
The call moves to Hold off if owner cash on this method recovers above the fiscal 2024 level for a full year or market value comes within 30% of a refreshed base, and to Buy only at or below 70% of base. The Oct 26, 2026 piece on capex carried a Watch call; this research supersedes that call.
2. A 47% operating margin, 11% research spending and a first-rate API
| Metric | Value |
|---|---|
| R&D share of revenue | 10.72%, research and development of $35,562M on $331,839M of revenue, fiscal 2026, calculated [1] |
| GAAP net margin | 40.31%, net income of $133,749M, fiscal 2026, calculated [1] |
| Clean figure | GAAP operating margin of 46.78%; net income includes $4,385M of net investment gains and $1,867M of derivative gains in other income, calculated [1] |
| API quality | 5 of 5 (below) |
| Toll-gate score, Office layer | 1 pass, 1 mixed, 2 partial |
Source: Microsoft Corporation filings and Golden Door Asset research.
API quality scores 5 of 5. Microsoft Graph is a documented REST API across Microsoft 365, with self-serve app registration [12]. Throttling limits are published [13].
The Azure MCP Server gives agents a tool surface [14]. Graph SDKs exist for C#, TypeScript and JavaScript, Java, Go, PHP and Python, among others [15].
AppSource, where Claude for Excel itself is listed, is the ecosystem proof [9].
2b. The Office toll gate under the Nov 10 facts
| Test | Score | Why |
|---|---|---|
| Owns the record | Pass | Anthropic routes full Excel work back to .xlsx, CSV or Claude for Excel; Enterprise Whiteboards and Sheets are off by default [8][9]. |
| Owns the connection | Partial | Claude for Excel installs through AppSource and the Admin Center and can run through Microsoft Foundry; a Mar 11, 2026 Anthropic article says Claude "powers Agent Mode natively inside Excel" [9][10]. The in-Excel versus in-Claude mix is not disclosed. |
| Outcome pricing | Mixed | Microsoft 365 Copilot is a per-user add-on at a $30 list price, with some usage meters [16]. |
| R&D on the gate | Partial | No Office, Excel or Fabric research split [1]. |
Source: Microsoft Corporation filings and Golden Door Asset research.
3. Growth: 18.80% in the September quarter
Revenue was $92,279M in the quarter ended Sep 30, 2026, up 18.80%, and $331,839M in fiscal 2026, up 17.79%, calculated [1][2]. Microsoft Cloud revenue was $63.9B, up 30% [3].
Microsoft 365 cloud revenue was $27,778M, up 17.24% from $23,694M, calculated, and Microsoft 365 commercial cloud grew 17% as reported [2]. The next quarterly results date is not yet announced; Microsoft's investor FAQ lists it as to be announced [17].
4. Agents ship inside the suite, and a rival ships inside it too
Microsoft sells Copilot as a seat add-on and adds usage meters around it, and on the Oct 28, 2026 call the Chief Financial Officer said E7 had reached "millions of paid seats" and paid Fabric customers were more than 44,000, up more than 50%, on the same call [16][18]. The company did not update its Copilot seat count that quarter [18].
The competitive test arrived Nov 10. Anthropic said documents, boards, sheets and dashboards "can stay in Claude" [8]. The same article sends full-functionality work back to Excel [8].
Claude for Excel does not run on Excel 2016 or 2019 perpetual licenses, which keeps part of the installed base out of reach of both products [9]. Claude also runs inside Excel beside Copilot, and through Microsoft Foundry [10].
The rival is, for now, also a tenant.
5. Retention: seats are the proxy, and seat growth is slowing
Microsoft does not disclose net revenue retention. The proxy is commercial seats: up 5% in the September quarter, against 6% in fiscal 2026, with growth "driven by installed base expansion across all customer segments, primarily small and medium business and frontline worker offerings" [1][2].
Revenue per user is carrying more of the growth, since Microsoft 365 commercial cloud revenue grew 17% on that 5% [2]. No absolute seat count is disclosed [1][2].
6. Free cash flow shrank as capex doubled
| Fiscal year | Operating cash flow | Capex | Stock pay | Owner cash, published method | Owner cash, full method |
|---|---|---|---|---|---|
| 2023 | $87,582M | $28,107M | $9,611M | $49,864M | $48,053.22M |
| 2024 | $118,548M | $44,477M | $10,734M | $63,337M | $59,156.56M |
| 2025 | $136,162M | $64,551M | $11,974M | $59,637M | $58,923.66M |
| 2026 | $182,935M | $115,948M | $12,405M | $54,582M | $31,563.27M |
Source: Microsoft Corporation filings and Golden Door Asset research.
All from the 10-K cash flow statements and notes; owner cash calculated [1]. The published method is operating cash flow less capex and stock pay.
The full method also removes the deferred revenue build ($9,361M in fiscal 2026), after-tax interest and dividends income ($2,660.73M), and $10,997M by which fiscal 2026 tax expense exceeded cash taxes paid ($32,185M against $21,188M), a timing gap that ran the other way in fiscal 2023 to 2025 [1]. Trailing to Sep 30, 2026, the published method gives $47,401M, the $47.40B anchor in the Oct 26 piece, calculated [1][2][7].
Capex excludes finance leases. Microsoft obtained $24,608M of right-of-use assets under finance leases in fiscal 2026, finance lease liabilities were $70,973M at Sep 30, 2026, and the 10-Q discloses $364.6B of datacenter leases signed but not yet commenced [1][2].
Counting the fiscal 2026 finance-lease additions as capex would cut owner cash to $6,955.27M, calculated [1].
7. Acquisitions
Spending on acquisitions, net of cash acquired and divestitures, plus purchases of intangible and other assets, was $5,978M in fiscal 2025, $1,743M in fiscal 2026 and $397M in the September quarter, against $69,132M in fiscal 2024, the year that included Activision Blizzard [1][2]. No deal in the past 24 months is large enough to move owner cash per share; the drop in owner cash comes from capex, not purchases.
8. Risks and catalysts
- Owner cash stays compressed by capex and leases for years [1][2].
- Seat growth keeps fading while Copilot stays undisclosed [2][18].
- Model-native work starts and stays outside Office, unmeasured on either side [8].
- OpenAI concentration: a related party, covered in the Oct 29 piece [2][6].
- New debt: $25,000M of notes due 2028 to 2066 issued under an Oct 29, 2026 underwriting agreement [4].
Catalysts: fiscal 2027 second-quarter results, date not yet announced [17]; the annual shareholders meeting on Dec 8, 2026 [5].
8b. The case against, scored
The strongest case for the stock: every path Anthropic offers for serious spreadsheet work lands on Microsoft's plane, revenue per seat is rising, Azure grew 48%, and $677B of commercial remaining performance obligation is contracted demand for the capacity being built [2][3][8][9].
| Point | Verdict | Why |
|---|---|---|
| Simple work can stay in Claude | Holds, unmeasured | No usage data on either side [8]. |
| Seat growth is slowing | Holds | 5% against 6% [1][2]. |
| Copilot seats undisclosed | Holds as a gap | No update on the call [18]. |
| The model vendor sits inside Excel | Partly holds | Microsoft keeps the plane and Foundry [9][10]. |
| Owner cash is falling as capex rises | Holds | Down 46.64% in two years [1]. |
| Leases and new notes add claims | Holds | $70,973M of finance lease liabilities, $364.6B uncommenced, $25,000M of notes [2][4]. |
Source: Microsoft Corporation filings and Golden Door Asset research.
9. Valuation: base value 83.14% below market value
Owner cash on the full method was positive in all four years tracked, so the standard allows a base value; the band low of the last three years is fiscal 2026, $31,563.27M, which is also the anchor [1]. Market value is $3,890,434.80M: the Nov 13, 2026 Nasdaq close times 7,426,194,552 shares on the 10-Q cover [2][11].
Net debt is $15,200M: total debt of $35,481M less $20,281M of cash and cash equivalents, with $44,228M of short-term investments left out under the standard; the $25,000M of November notes is treated as raising debt and cash equally until the next 10-Q, calculated [2][4].
| Case | Assumption | Owner cash, year 1 to year 5 | Equity value | Vs market value |
|---|---|---|---|---|
| Bear | 3% a year, capex stays at the fiscal 2026 share of operating cash | $32,510.17M to $36,590.48M | $526,636.15M | -86.5% |
| Base | 8% a year | $34,088.33M to $46,376.80M | $655,758.72M | -83.1% |
| Bull | 14% a year, close to recent revenue growth | $35,982.13M to $60,772.38M | $843,755.96M | -78.3% |
Source: Microsoft Corporation filings and Golden Door Asset research.
All at a 9% discount rate and 3% terminal growth, calculated [1][2][11]. Terminal value is 75% to 79% of enterprise value.
At 8% the base is $792,819.73M; at 10%, $557,931.68M.
Reverse DCF. From the $31,563.27M anchor, the market value implies 57.08% a year of owner cash growth for five years at 9%, 50.61% at 8% and 62.92% at 10%, calculated.
10. Superintelligence angle: tailwind for the plane, mixed for the seat
Tailwind for Azure and Foundry, which host the models, including Claude [3][10]. Mixed for Office: the record stays in Excel, but per-seat pricing faces work that agents can do without a seat [8][16].
11. Leadership and control
Satya Nadella has been Chief Executive Officer since February 2014 and Chairman since June 2021; Amy Hood has been Chief Financial Officer since 2013; Judson Althoff became Chief Executive Officer of Microsoft Commercial Business in October 2025 [1]. Nadella and Hood led the Oct 28, 2026 call [18].
There is no controlling holder and one class of common stock. The 5% holders in the 2026 proxy are Vanguard Capital Management at 7.48% and BlackRock at 7.30%, as the proxy reports them from Schedule 13G filings of Apr 30, 2026 and Feb 13, 2024 [5].
Reid Hoffman and Hugh Johnston are not standing for re-election at the Dec 8, 2026 meeting [5]. Hood adopted a Rule 10b5-1 trading plan on Jun 10, 2026 [1].
Style: Nadella runs a platform-first company that is spending heavily ahead of contracted demand and says so; the capex is a choice, disclosed quarter by quarter [2][18].
12. Questions for management, and the predictions being tracked
Question one: how many paid Microsoft 365 Copilot seats are there, and what share of Copilot revenue is usage-based?
Question two: how much of fiscal 2027 capex is contracted to specific customers, and to OpenAI?
Question three: what share of Excel work now runs with a third-party agent inside it?
Question four, on conviction: when does owner cash after stock pay and capex return to the fiscal 2024 level? The answer moves conviction toward 4 or 2.
Prediction one: second-quarter fiscal 2027 revenue growth at or above 16% (70%).
Prediction two: Microsoft 365 commercial seat growth at or below 5% in that quarter (60%).
Prediction three: cash capex above $40,000M in that quarter (65%).
Prediction four: no updated paid Copilot seat count with those results (50%).
Prediction five: fiscal 2027 owner cash on the full method below $40,000M (60%).
Prediction six: market value stays above the $655,758.72M base at 3 months (95%), 6 months (95%) and 12 months (90%).
Bottom line: the gate holds, the price assumes the build pays back fast
Anthropic's launch confirmed that serious spreadsheet work still runs through Excel and Microsoft 365. That protects the Office toll. It does not change the cash math: owners kept $31,563.27M in fiscal 2026 after capex and stock pay, down 46.64% in two years, and the market value assumes that figure grows about 57% a year for five years.
Avoid, conviction 3 of 5, until owner cash or the price closes the gap.
Source: Microsoft Forms 10-K for fiscal 2026, 10-Q for the quarter ended Sep 30, 2026, 8-Ks of Oct 28 and Nov 4, 2026, and the 2026 proxy statement; Golden Door Research calculations.
Company Profile
MSFT Stock Profile →Updates: Microsoft Now Spends 69.39% of Its Operating Cash Building the Superintelligence Grid
Related Coverage & Peer Deep-Dives
View All →Dynatrace: Buy on Profitable Enterprise Observability at a 32% Discount to Base DCF
Dynatrace combines 21.4% TTM revenue growth and 81.1% gross margin with positive 12.7% GAAP operating margin and $578.7M of GAAP FCF, trading at $42.63 versus our $62.81 5-year DCF base value.