
Golden Door Asset · Investment Committee Research Brief
Oracle
Published Oct 28, 2026 · Data as of Oct 28, 2026
ORCL · Research
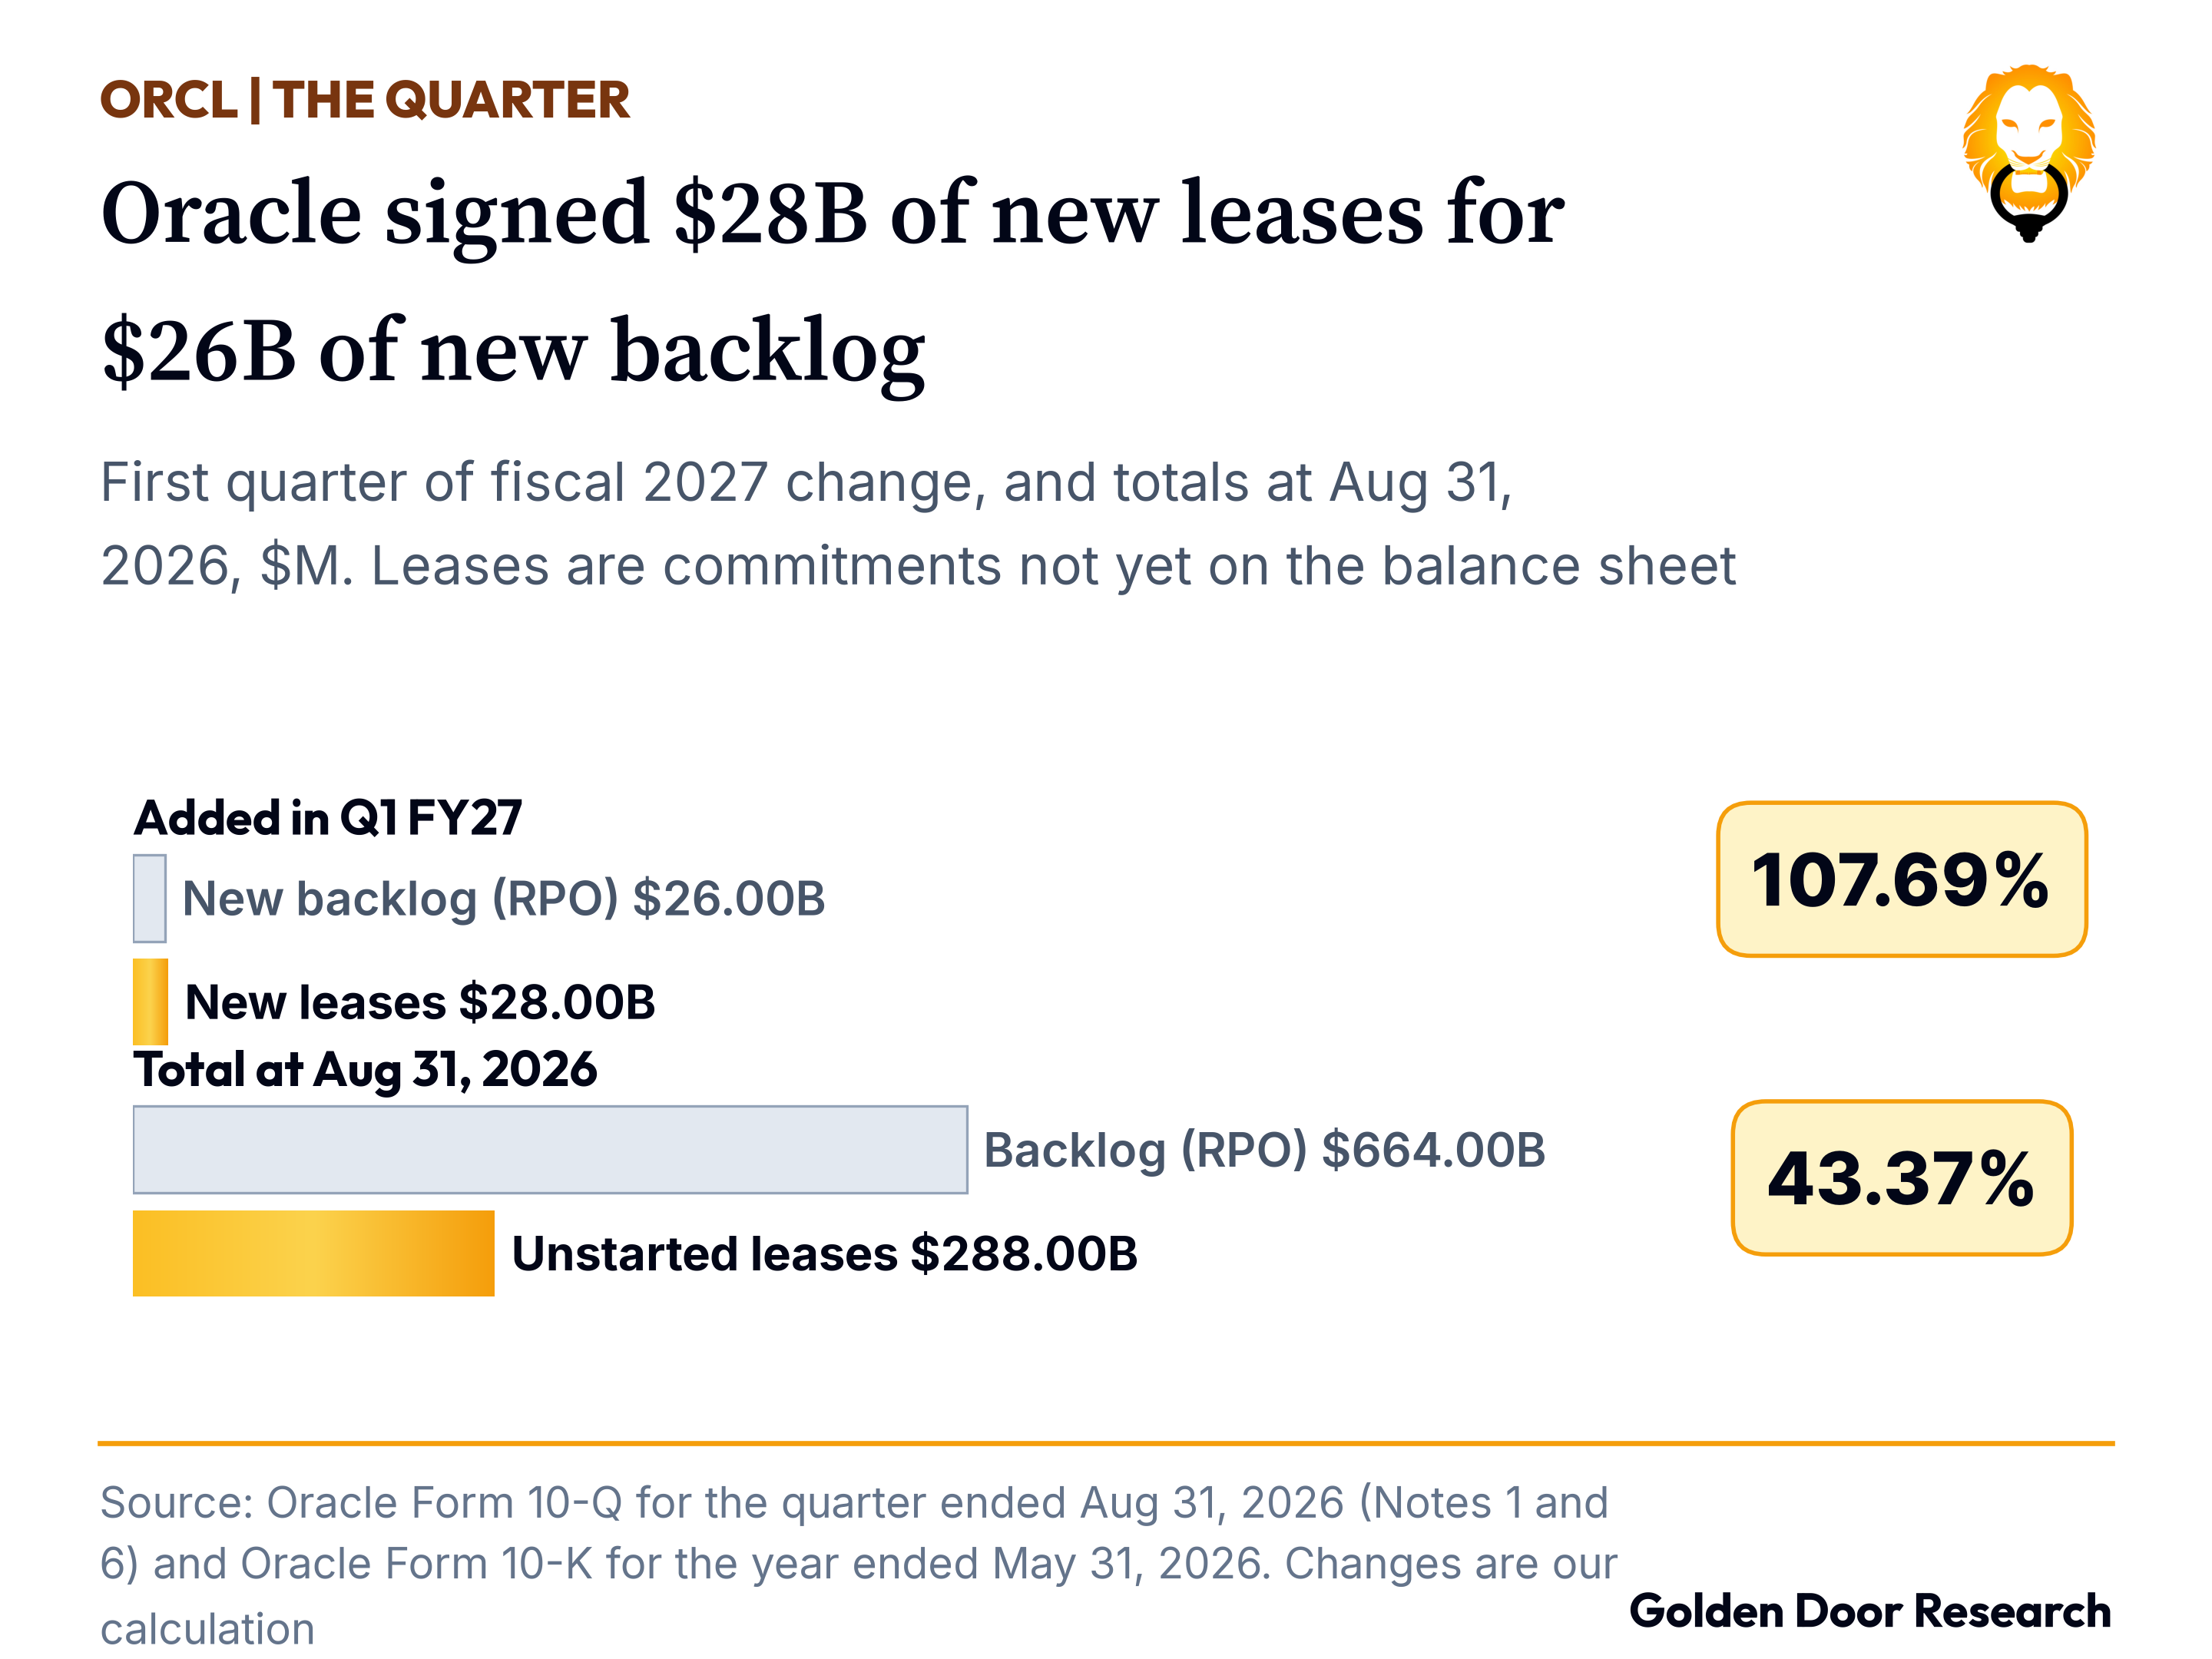
Oracle's $20B cap leaves out the $288B it signed in data center leases
At its Investor Day on Oct 28, Oracle capped new money at $20B through fiscal 2030 and said new contracts will not need incremental capital from Oracle. Both promises leave out leases.
At its Investor Day on Oct 28, Oracle capped new money at $20B through fiscal 2030 and said new contracts will not need incremental capital from Oracle. Both promises leave out leases.
In the first quarter of fiscal 2027, Oracle added $26B of backlog and $28B of data center leases that have not started yet. The database is a toll gate.
The GPU business is a spread business, and the leases are where the spread gets paid for. This research reads the filings, the Investor Day release and the Sep 10 call to separate the two.
1. What Oracle is today
Oracle is two companies sharing one balance sheet. The first is the database and the applications built on it: software license and support of $24.54B in FY26 and cloud applications of $15.89B [3].
That business runs on contracts customers rarely leave, because the record of the business lives in it. The second is Oracle Cloud Infrastructure, which grew from $10.23B to $18.10B in FY26 (76.87%) and from $3.35B to $7.39B in the first quarter (120.73%) [3][4].
Cloud infrastructure is now 38.19% of quarterly revenue, up from 22.42% a year earlier [4].
Total revenue was $67.36B in FY26 and $19.35B in the quarter to Aug 31 [3][4]. Management reaffirmed at least $90B of FY27 revenue and set a target of more than $225B for FY30 [1].
$1,000/yr. The full notes, valuation, exhibits, risks, archive and exports across 130 stocks.
Company Profile
ORCL Stock Profile →Updates: Oracle Spends More Than Its Operating Cash on Capex, Turning Owner Cash Negative
Related Coverage & Peer Deep-Dives
View All →Claude Sheets Still Sends Serious Work Back to Excel, but Microsoft's Owner Cash Fell 46.64% in Two Years and Its Market Value Assumes 57% Yearly Growth
Anthropic's new sheets still send serious work back to Excel, but owner cash after capex and stock pay fell 46.64% in two years and the market value assumes about 57% yearly growth.