
Golden Door Asset · Investment Committee Research Brief
PagerDuty, Inc.
Published Oct 29, 2026 · Data as of Oct 29, 2026
PD · Research
PagerDuty's customers spend less, and stock pay takes 69% of its free cash
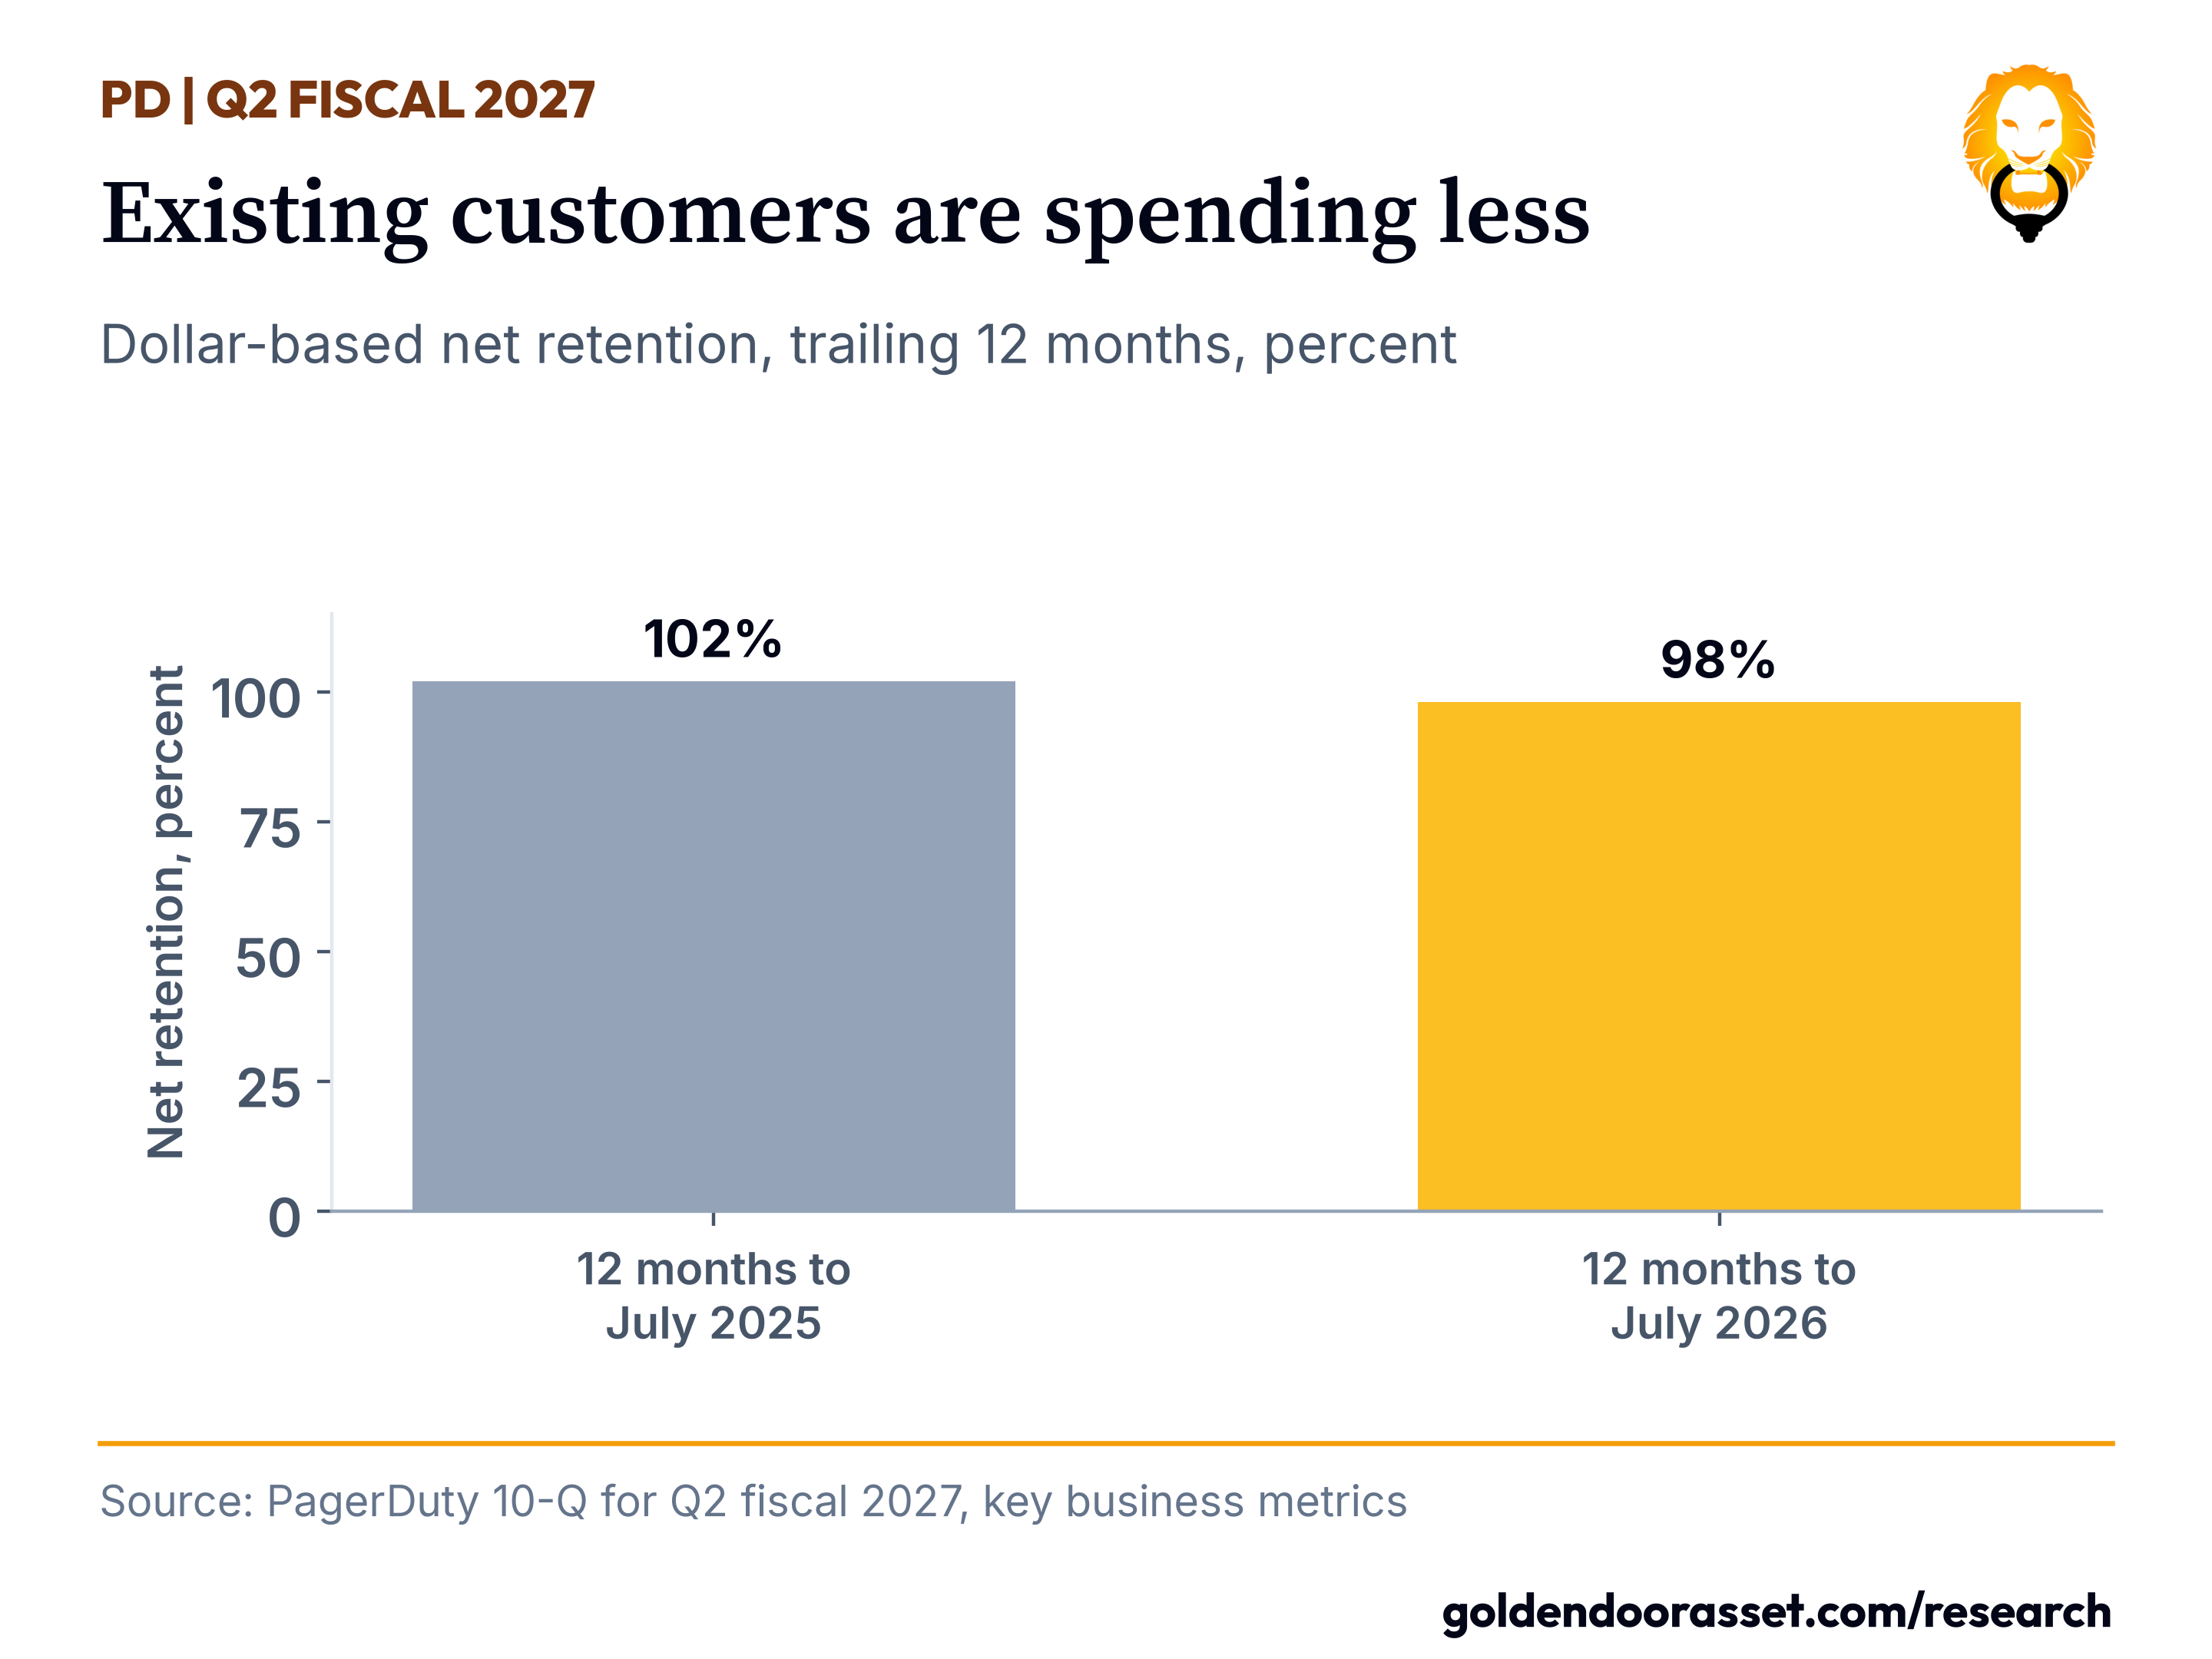
PagerDuty, which routes urgent incidents to the people and agents who fix them, grew revenue 0.8% in its fiscal second quarter while dollar-based net retention fell to 98% from 102%. It turns about $117M of trailing free cash flow into about $37M for owners after stock pay, and it is cutting about 15% of staff.
1. Summary
The question this piece answers: PagerDuty is profitable on paper and is moving its pricing away from seats, but its existing customers are now spending less each year. Is the incident layer worth owning at about $1.58B of enterprise value?
What you will get from each section. The Thesis explains why the system that wakes someone up when software breaks could matter more when agents run operations, and scores PagerDuty on our three gate tests. The Valuation sets today's multiples against a five-year bear, base and bull case built on owner free cash flow.
The Financial update shows the flat quarter, the margin gains from cost cuts and where the cash went. The Risks develop the two threats that matter most: seat compression at large customers alongside bundling by bigger platforms, and a leadership and restructuring reset with the 2028 convertible notes behind it.
The last section names the next catalyst and gives our position.
Our position: avoid. Profit is rising because costs are falling, not because customers are buying more, and our base case is worth less than today's value (0.73x).
Key numbers
Q2 fiscal 2027 revenue rose 0.8% to $124.44M [1].
Dollar-based net retention fell to 98% from 102%, and ARR was $501.4M against $498.9M a year earlier [1].
Operating income rose to $10.24M from $3.57M as operating expenses fell 6.6% [1].
Trailing free cash flow was about $117.46M and stock pay $80.53M, so owner free cash flow was about $36.93M, our calculation [1][2].
PagerDuty announced a cut of about 15% of headcount on Aug 26, 2026 [3].
$1,000/yr. The full notes, valuation, exhibits, risks, archive and exports across 130 stocks.
Company Profile
PD Stock Profile →Related Coverage & Peer Deep-Dives
View All →Claude Sheets Still Sends Serious Work Back to Excel, but Microsoft's Owner Cash Fell 46.64% in Two Years and Its Market Value Assumes 57% Yearly Growth
Anthropic's new sheets still send serious work back to Excel, but owner cash after capex and stock pay fell 46.64% in two years and the market value assumes about 57% yearly growth.