Golden Door Asset
BenchmarkResearchFinancials
Sign InFull Access

Golden Door Asset

Public software investment firm focused on durable compounders, supported by our software quality ratings and research.

Ratings & Research

  • Research Library
  • R&D Benchmark
  • Methodology
  • Financial Model
  • Investment Mandate
  • Full Access

Company

  • About Us
  • Member Hub
  • Member Sign In
  • Contact Us

Legal

  • Privacy
  • Terms
© 2026 Golden Door Asset. All rights reserved.
Loading equity research...

Golden Door Asset · Investment Committee Research Brief

BILL Holdings, Inc.

Published Nov 21, 2026 · Data as of Nov 20, 2026

Research Library/BILLBILL Holdings, Inc.
BILL Model →

BILL · Research

BILL Holdings (BILL) Moves More Volume Than Corpay (CPAY) Corporate Payments but Earns 42% Less per Dollar

By Vijar Kohli

Last quarter BILL Holdings (BILL) processed more payment volume than Corpay (CPAY) corporate payments, $101.80B against $95.30B, but earned 34.75 basis points on it against Corpay's 59.95, or 42% less per dollar. TPG (TPG) and Corpay have agreed to take BILL private, and Corpay names better payment monetization as a priority for the business.

56.44·NeutralAs of Nov 8, 2026▲ +7.1 YoY#50 RatedResearchPublished Nov 21, 2026 · Data as of Nov 20, 2026· 2 min read · 2 exhibitsUpdated

On Nov 19, 2026, TPG (TPG) and Corpay (CPAY) agreed to take BILL Holdings (BILL) private [1][11]. Last quarter BILL processed $101.80B of payment volume, more than the $95.30B through Corpay's corporate payments unit, but earned 34.75 basis points on it against Corpay's 59.95, or 42% less per dollar, calculated [4][6][9].

Corpay names better payment monetization as a priority for the business [3].

Exhibit 1Financial Schedule
MetricValuePeriod
Total payment volume$101.80B, up 14.00%Quarter to Sep 30, 2026 [6]
Revenue per dollar of volume34.75 bps for BILL vs 59.95 bps for Corpay (CPAY) corporate paymentsQuarter to Sep 30, 2026, calculated [4][9]
Owner cash after stock pay$60.17M, including $148.0M of interest on customer fundsTwelve months to Sep 30, 2026, calculated [4][5][6]

Source: BILL Holdings, Inc. filings and Golden Door Asset research.
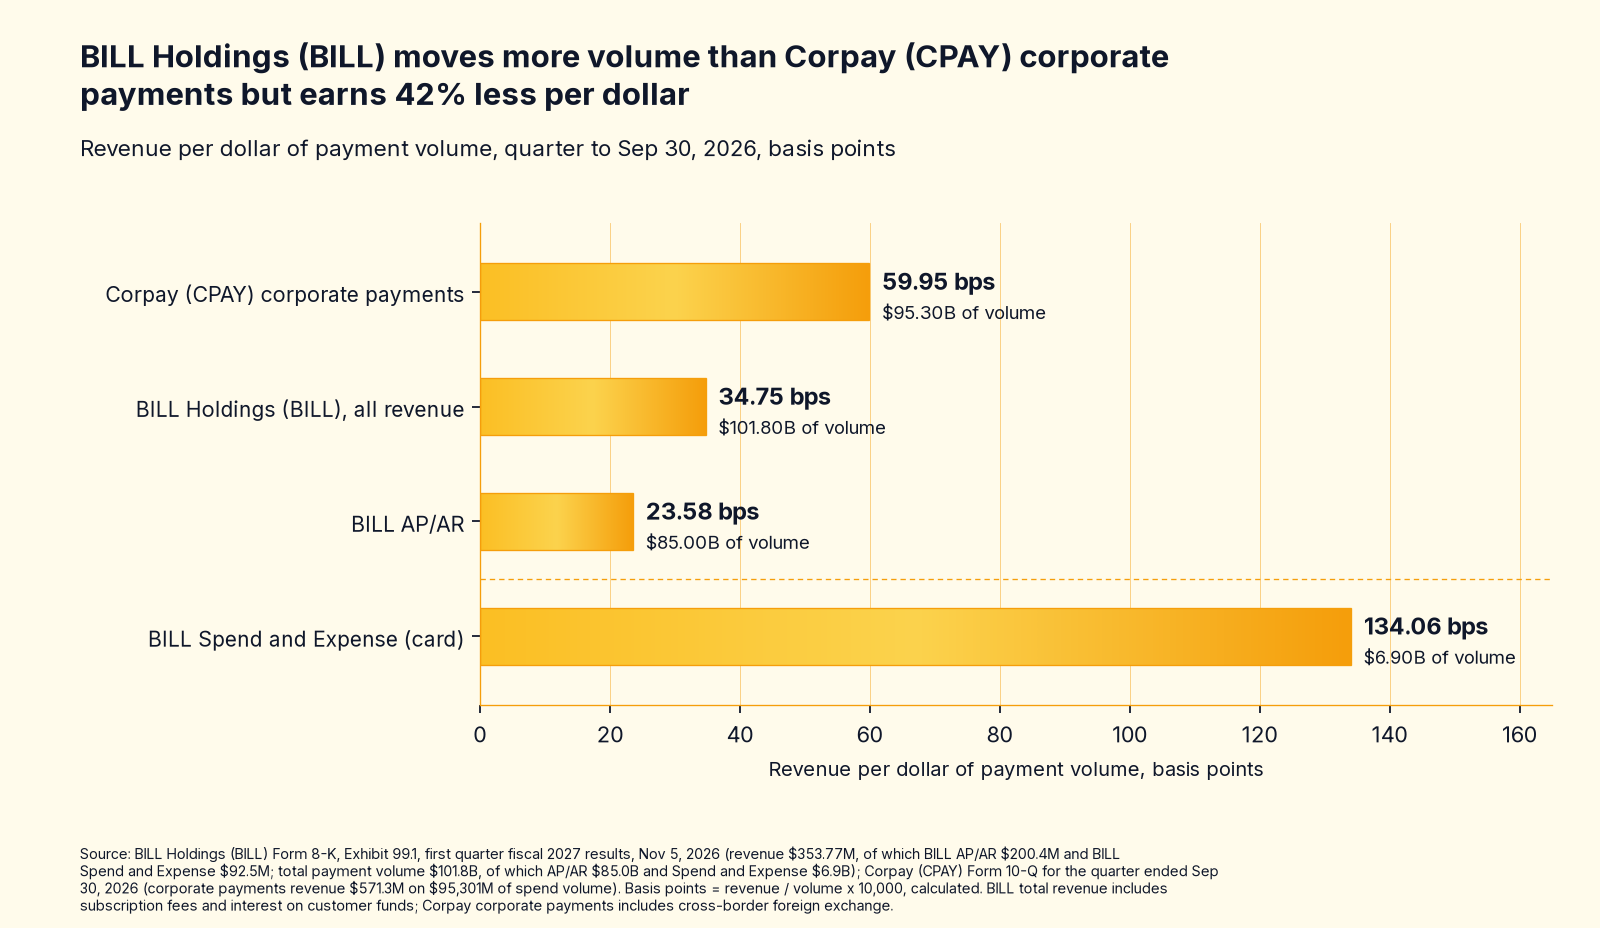
Revenue per dollar of payment volume in the quarter to Sep 30, 2026: Corpay (CPAY) corporate payments 59.95 basis points on $95.30B; BILL Holdings (BILL) all revenue 34.75 basis points on $101.80B; BILL AP/AR 23.58 basis points on $85.00B; BILL Spend and Expense 134.06 basis points on $6.90B.
Exhibit 1. BILL Holdings (BILL) moves more volume than Corpay (CPAY) corporate payments but earns 42% less per dollar.

1. BILL Holdings (BILL) earned 42% less per dollar than Corpay (CPAY), and fiscal 2026 revenue grew 9.66% on the current basis

In the September quarter BILL Holdings (BILL) processed $101.80B, 6.82% more than the $95.30B through the corporate payments unit of Corpay (CPAY), but earned $353.77M in revenue against Corpay's $571.30M: 34.75 basis points against 59.95, or 42% less per dollar, calculated [6][9]. AP/AR earned only 23.58 basis points on $85.00B.

BILL's card product earned 134.06 basis points on $6.90B, calculated [6]. Corpay's mix includes cross-border foreign exchange, so the full gap is not reachable.

Corpay's own list of priorities for BILL starts with "improve monetization through new payment options" [3].

For BILL Holdings (BILL), the widely quoted figure of $1.65B in fiscal 2026 revenue, up 13%, is correct for the 10-K as filed: $1,653.16M against $1,462.57M [5]. Since Jul 1, 2026, however, BILL has netted card rewards against revenue and restated prior periods.

On that basis fiscal 2026 revenue was $1,305.56M, up 9.66% from $1,190.58M, calculated [7].

The latest quarter grew 12.51% to $353.77M, and core revenue (subscriptions plus transaction fees) grew 14% to $316.40M [4][6]. Guidance for the year to Jun 30, 2027 is $1,433.50M to $1,463.50M of revenue, up 10% to 12%, and $466.00M to $486.00M of non-GAAP operating income [6].

Interest on customer funds was $37.40M in the quarter, and those earnings fall when rates fall [6].

BILL Model

On this page

  1. 1. BILL Holdings (BILL) earned 42% less per dollar than Corpay (CPAY), and fiscal 2026 revenue grew 9.66% on the current basis
  2. 2. Call: Exit or Sell, conviction 4 of 5. The spread to the offer pays less than a 9% hurdle for the break risk
  3. 3. The 14.46% operating margin came after a 37.08% cut to research spending
  4. 4. BILL Holdings (BILL) ships quickly, but agents still cannot pay a bill through it
  5. 5. Direct AP/AR retention was 95%, and the business count fell 4.65%
  6. 6. Owner cash after stock pay was $60.17M, and float interest was larger than that
  7. 7. The deal: TPG (TPG) takes control, Corpay (CPAY) buys about a third, and the structure mirrors AvidXchange
  8. Sponsor equity covers about 43% of the cost, and committed debt plus cash at BILL Holdings (BILL) covers the rest
  9. The buyers' break fee is larger than in the AvidXchange deal
  10. Holders of 11.1% of the vote are committed, and state regulators and antitrust review set the timing
  11. The take-rate gap is the buyers' main lever
  12. 8. Risks and catalysts: regulators, not the vote, decide the timing
  13. 9. Valuation: no base value is set, and the price needs 54.72% annual growth in owner cash
  14. 10. Superintelligence angle: mixed. Agents threaten seat fees but still need a payment rail
  15. 11. Leadership: the founder stays CEO, and the activist holder backs the sale
  16. 12. Antitrust timing and the buyers' break fee are the open questions
Unlock the full note with Full Access

$1,000/yr. The full notes, valuation, exhibits, risks, archive and exports across 130 stocks.

Full Access

Golden Door Membership

Unlock the full institutional underwriting, Bear/Base/Bull valuation cases, exhibits, and permanent research archive across 130 software companies.

Remaining in this report (15 sections)+6 exhibits
  1. 1.2. Call: Exit or Sell, conviction 4 of 5. The spread to the offer pays less than a 9% hurdle for the break risk
  2. 2.3. The 14.46% operating margin came after a 37.08% cut to research spending
  3. 3.4. BILL Holdings (BILL) ships quickly, but agents still cannot pay a bill through it
  4. 4.5. Direct AP/AR retention was 95%, and the business count fell 4.65%
  5. 5.6. Owner cash after stock pay was $60.17M, and float interest was larger than that

Sources

  1. [1]BILL Holdings, Inc., "BILL Agrees to be Acquired by TPG in Partnership with Corpay," Nov 19, 2026, 5:46 PM ET, filed as Exhibit 99.1 to Form 8-K, Nov 20, 2026.
  2. [2]Corpay, Inc., "Corpay Invests Alongside TPG to Acquire BILL," Nov 19, 2026, furnished as Exhibit 99.1 to Form 8-K, Nov 19, 2026.
  3. [3]Corpay, Inc., "BILL Take Private Transaction," investor update call presentation, Nov 19, 2026.
  4. [4]BILL Holdings, Inc., Form 10-Q for the quarter ended Sep 30, 2026 (balance sheet, cash flows, Notes 4, 7 and 10, key metrics, cover page).
  5. [5]BILL Holdings, Inc., Form 10-K for the fiscal year ended Jun 30, 2026.

Company Profile

BILL Stock Profile →
BILLBILL Holdings, Inc.

Updates: BILL Rebated Over Half Its Card Revenue to Buy Volume, and Its Credit Book Eats the Owner Cash

Related Coverage & Peer Deep-Dives

View All →
INTU72.02 · StrongSector Peer
Free summary

Intuit (INTU) Sells Mailchimp to Refocus on the Ledger and the Tax Return

Intuit (INTU) is selling Mailchimp to Bending Spoons (BSP) so it can win customers from inside the small-business ledger, payroll and the tax return, through what it calls lead to cash. Mailchimp revenue has stalled, down 1.26% in the latest quarter, while the rest of Intuit grew 13% to 17% a year.

Intuit Inc.Nov 21, 2026 · Data as of Nov 19, 2026
← All Research LibraryMore BILL Research →
BILL Model →
6.
7. The deal: TPG (TPG) takes control, Corpay (CPAY) buys about a third, and the structure mirrors AvidXchange
  • 7.Sponsor equity covers about 43% of the cost, and committed debt plus cash at BILL Holdings (BILL) covers the rest
  • 8.The buyers' break fee is larger than in the AvidXchange deal
  • 9.Holders of 11.1% of the vote are committed, and state regulators and antitrust review set the timing
  • 10.The take-rate gap is the buyers' main lever
  • 11.8. Risks and catalysts: regulators, not the vote, decide the timing
  • 12.9. Valuation: no base value is set, and the price needs 54.72% annual growth in owner cash
  • 13.10. Superintelligence angle: mixed. Agents threaten seat fees but still need a payment rail
  • 14.11. Leadership: the founder stays CEO, and the activist holder backs the sale
  • 15.12. Antitrust timing and the buyers' break fee are the open questions
  • Locked analytical exhibits (6)

    Owner Cash Waterfall & 5x5 Sensitivity Matrix
    Owner Cash Waterfall
    5x5 Sensitivity Matrix
    Bear/Base/Bull Valuation & RisksAll Exhibits & Financial Schedules130-Stock Archive & CSV Exports
    Get Full Access→
    Instant web & archive accessMember Sign In

    Not ready yet? Get the free opening of each weekly research note by email.

  • [6]BILL Holdings, Inc., Form 8-K, Exhibit 99.1, first quarter fiscal 2027 results, Nov 5, 2026.
  • [7]BILL Holdings, Inc., Form 8-K, Exhibit 99.1, quarterly results recast for the card rewards presentation change, Oct 15, 2026.
  • [8]AvidXchange Holdings, Inc., Form 8-K, Item 1.01, merger agreement with TPG and Corpay affiliates, May 7, 2025.
  • [9]Corpay, Inc., Form 10-Q for the quarter ended Sep 30, 2026 (segment results, AvidXchange investment note).
  • [10]Nasdaq.com, BILL Holdings (NYSE: BILL) historical quotes, official consolidated closes for Nov 13, 16, 18, 19 and 20, 2026.
  • [11]BILL Holdings, Inc., Form 8-K, Items 1.01, 8.01 and 9.01, Nov 20, 2026, with the Agreement and Plan of Merger (Exhibit 2.1) and the form of Voting and Support Agreement (Exhibit 10.1).
  • [12]BILL Holdings, Inc., definitive proxy statement for the 2026 annual meeting, filed Oct 27, 2026.
  • [13]BILL Holdings, Inc., Form 8-K, Item 1.01, cooperation agreement with Starboard Value, Oct 16, 2025.
  • [14]BILL developer documentation, "BILL MCP Server" (beta; read-only; creating, editing, approving and paying not yet available), read Nov 20, 2026.
  • [15]SEC XBRL company facts for BILL Holdings (fiscal 2024 and 2025 operating cash flow, stock pay, capital spending, interest income from the 10-K filings).
  • [16]Corpay, Inc., June 2025 investor presentation, p. 20 (AvidXchange terms and 2024 financials).
  • FICO63.8 · StrongSector Peer
    Free summary

    Fair Isaac: 51.7% Credit-Scoring Operating Margin

    FICO converts $2.53B of FY2026 revenue into a 51.7% GAAP operating margin and $884.5M of owner cash on just $2.1M of capex.

    Fair Isaac CorporationNov 8, 2026 · Data as of Sep 30, 2026
    DSGX68.53 · StrongSector Peer
    Free summary

    Descartes Owns the Customs Filing Lane and Spends Nearly All Its Cash Buying More Lanes

    Descartes turns 35% of revenue into owner cash from a freight filing network, but growth from existing customers is under 10% and deals since early 2025 used about all the cash it made.

    The Descartes Systems Group Inc.Nov 1, 2026 · Data as of Oct 31, 2026
    Industry ResearchIndustry Research
    Golden Door

    Clouds Own the Servers. Database Renters Kept the Margin.

    Microsoft (MSFT) and Oracle (ORCL) lost between 2.4 and 9.86 points of cloud margin in their latest quarter as new data center capacity came online, while Snowflake (SNOW), MongoDB (MDB) and Elastic (ESTC) held gross margins of roughly 71% to 77% on infrastructure they rent from those same clouds. Owning servers turns every new data center into depreciation that lands before the revenue does; renting turns it into a usage bill that grows with the customer.

    Golden Door AssetNov 21, 2026 · Data as of Nov 21, 2026